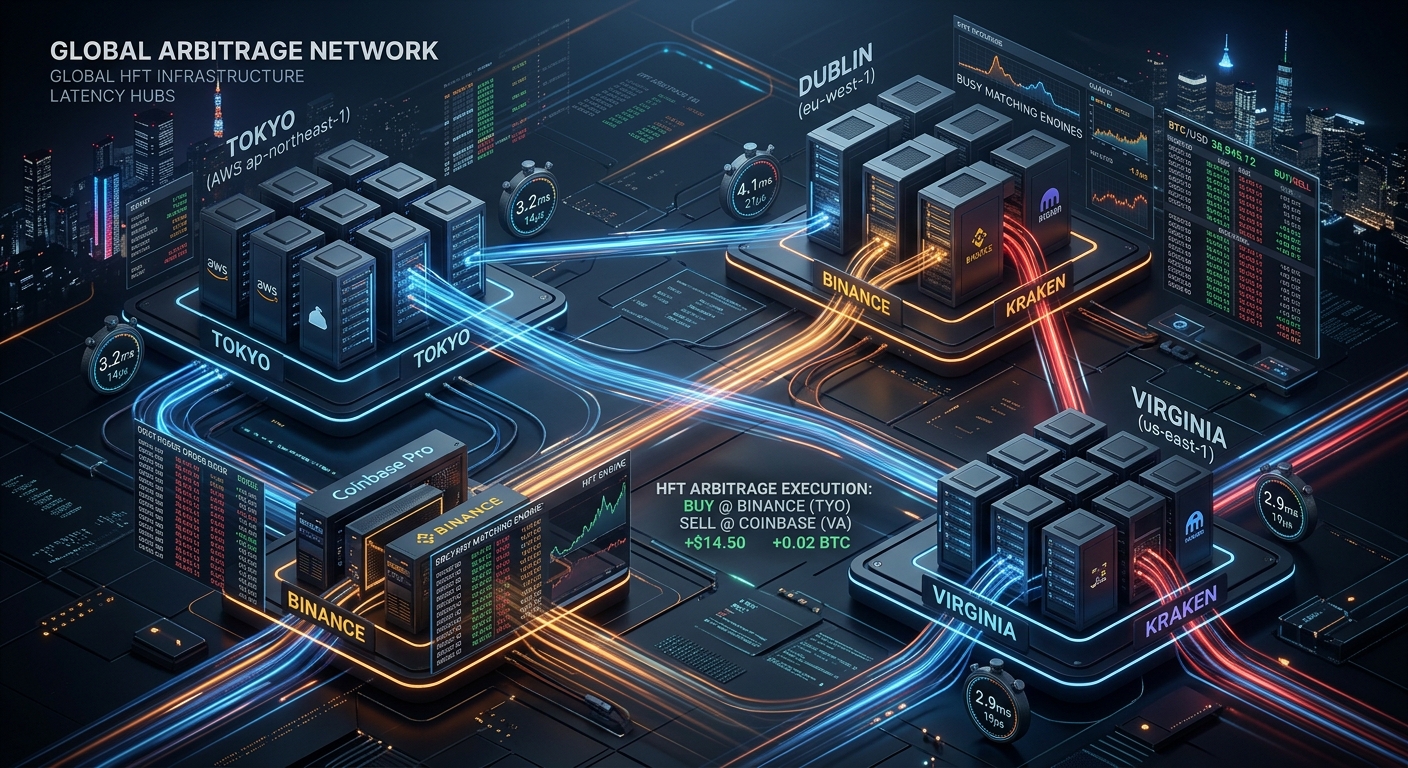
In high-frequency cryptocurrency arbitrage, time is literally measured in microseconds.
When a sudden macro announcement or a multi-million-dollar liquidation moves Bitcoin on Binance, a cross-exchange price dislocation opens up across OKX, Bybit, Kraken, and Coinbase.
That profitable price gap does not last for minutes. It does not even last for seconds.
It exists for exactly 15 to 45 milliseconds before dozens of automated quantitative trading algorithms detect it, fire simultaneous orders, and close the spread.
If your trading bot is running on a standard home broadband connection in London (ping: 180ms to Tokyo) or polling a REST API endpoint every 500ms, you will never capture a single cent of that arbitrage. You will arrive late, buy after the price has already adjusted, and suffer 100% negative execution drag.
To win in automated cross-exchange and triangular arbitrage, you need exchanges that deliver sub-millisecond matching engines, raw Level-2 incremental WebSocket streams, generous API rate limits, institutional FIX protocols, and predictable cloud server colocation.
In this 2026 quantitative engineering guide, we benchmark and rank the best cryptocurrency exchanges for low-latency arbitrage execution, map their physical cloud server hosting regions, evaluate API architectures, and examine four real-world HFT case studies.
The Master 2026 Low-Latency Arbitrage Exchange Benchmark
The table below compares the world’s leading trading venues across Matching Engine Internal Latency, Primary Cloud Hosting Region, API Protocol Support, Rate Limit Capacities, and Arbitrage Viability Rating:
| Exchange & Architecture | Internal Engine Latency | Primary Server Hosting Region | Best API Protocol | Order Rate Limit Capacity | Best Arbitrage Strategy |
|---|---|---|---|---|---|
| 1. OKX (Unified V5) | < 3.5 ms | AWS Tokyo (ap-northeast-1) | WebSocket v5 & FIX 4.4 | 60 orders / sec (Expandable to 150/s) | #1 Cross-Exchange & Altcoin Spatial Arbitrage |
| 2. Binance Global | < 4.0 ms | AWS Tokyo (ap-northeast-1) | WebSocket Streams & Ed25519 REST | 1,200 orders / min (Weighted rules) | #1 High-Volume Spot & USD-M Futures Arbitrage |
| 3. Bybit (UTA Engine) | < 5.0 ms | AWS Singapore (ap-southeast-1) | WebSocket Linear & Spot v5 | 100 orders / sec (VIP tiers) | #1 Spot vs. Perpetual Funding Rate Carry Arbitrage |
| 4. Coinbase Exchange | < 6.5 ms | AWS Virginia (us-east-1) | Institutional FIX & Advanced WS | 50 req / sec (Private endpoints) | #1 US Regulated Institutional Fiat USD Arbitrage |
| 5. Deribit (Custom Engine) | < 1.2 ms (Fastest) | Equinix / OVH Amsterdam (NL) | Raw WebSocket RPC (JSON-RPC 2.0) | 100 req / sec (Dedicated IP) | #1 Options & Futures Volatility Arbitrage |
| 6. Kraken Pro | < 9.0 ms | AWS Dublin (eu-west-1) | WebSocket v2 & REST | Up to 150 tokens/tier pool | #1 European EUR/USD Cross-Currency Arbitrage |
| 7. Gate.io | < 8.0 ms | AWS Tokyo / Singapore | WebSocket v4 & Spot API | 300 req / sec (Generous) | #1 Long-Tail Altcoin Triangular Arbitrage |
| 8. KuCoin | < 11.0 ms | AWS Tokyo (ap-northeast-1) | WebSocket Push Level-2 | 45 orders / sec | #1 Mid-Cap Gem Liquidity Gap Arbitrage |
1. The Anatomy of Arbitrage Latency: Where Every Millisecond is Lost
To build a winning latency arbitrage bot, you must understand the four components of the Total Execution Latency Stack:
[ THE 4-STAGE LATENCY STACK IN CRYPTO ARBITRAGE ]

  1. MARKET DATA INGRESS (Feed Latency): 1.0ms - 8.0ms
     - Exchange matching engine emits trade/order book delta.
     - Pushed through WebSocket server to your server.

  2. ARBITRAGE LOGIC & SIGNAL COMPUTATION: 0.05ms - 0.5ms
     - C++ / Rust / Go algorithm parses JSON/binary packet.
     - Evaluates triangular or spatial spread matrix, checks net fees, generates order.

  3. NETWORK WIRE PROPAGATION (Transport Latency): 0.8ms - 150.0ms (BIGGEST VARIABLE!)
     - TCP packet travels across physical fiber cables between your server and exchange.
     - Colocated AWS Tokyo to AWS Tokyo: 1.2ms | Home broadband to Tokyo: 180.0ms.

  4. MATCHING ENGINE QUEUE & INGRESS: 2.0ms - 10.0ms
     - Exchange matching engine validates digital signature, checks balances, matches resting book.
If your network transport latency is 150ms, the price gap will be dead on arrival. If you colocate your servers in the same cloud data center as the exchange matching engine, your network wire latency drops to 1.2 milliseconds, giving your bot a 99% probability of winning the fill.
2. Deep Dive: The Top 3 Low-Latency Arbitrage Venues
1. OKX — The King of Cross-Exchange Latency & API Elegance
ap-northeast-1). Placing your trading node in the same AWS region yields a sub-2.0ms Round-Trip Time (RTT) to both OKX and Binance matching gateways simultaneously.2. Binance Global — High-Throughput Titan with Dedicated WebSocket Streams
stream.binance.com) and USD-M Futures (fstream.binance.com), preventing spot market data spikes from throttling derivative order streams.3. Deribit — The World's Fastest Pure Matching Engine
3. REST API vs. WebSocket vs. FIX Protocol: The Speed Hierarchy
How your trading bot communicates with the exchange matching engine determines your execution ceiling:
[ API PROTOCOL SPEED & EFFICIENCY COMPARISON ]

  Protocol Type         Handshake / Overhead       Round-Trip Latency       Best Use Case
  ----------------------------------------------------------------------------------------------------
  REST (HTTP/1.1)       Full TLS handshake/req     60ms - 250ms             Account balances, withdrawals (USELESS for Arb)
  REST (HTTP/2 KeepAlive) Persistent TCP session   15ms - 40ms              Secondary order cancellations
  WebSocket (JSON)      Persistent Full-Duplex     2ms - 8ms                Real-time L2 order book feeds & fast execution
  WebSocket (Protobuf)  Binary serialized stream   1ms - 3ms                Ultra-fast raw order book diffs (OKX/Bybit)
  FIX 4.4 Protocol      Binary/Tag-value socket    0.8ms - 2.5ms            Institutional DMA (Coinbase/Deribit/OKX)
The Quantitative Golden Rule: For automated arbitrage, never poll REST endpoints. Always build your trading engine using persistent WebSocket connections or FIX protocol sockets.
4. The Colocation Geographic Blueprint: Tokyo vs. Virginia vs. Dublin
If you are running cross-exchange arbitrage, where should your cloud servers live?
ap-northeast-1) or AWS Singapore (ap-southeast-1). This provides sub-3ms latency between all four major Asian/Offshore liquidity hubs.eu-west-1) or Equinix Amsterdam (AM4).Real-World Case Study 1: The 12-Millisecond Cross-Exchange Arbitrage Race
A massive market buy on Binance pushed the price of Ethereum from $3,400.00 to $3,425.00:
Competitor A (Home Broadband Bot in London, REST API, Ping: 195ms to Tokyo):
Competitor B (Colocated AWS Tokyo Instance, Rust Engine, WebSocket v5, Ping: 1.4ms):
Real-World Case Study 2: Triangular Arbitrage on a Single Exchange (Binance Spot)
Triangular arbitrage eliminates cross-exchange network latency entirely by executing a three-leg loop on a single order book (e.g. USDT -> BTC -> SOL -> USDT):
Real-World Case Study 3: The REST Rate Limit Crash Disaster (HTTP 429 Ban)
During a flash crash on Solana, a bot using REST API polling sent 80 requests in 2 seconds to check open order status:
Real-World Case Study 4: Ed25519 Cryptographic Signature Optimization (Saving 1.1ms)
A quant fund bench-marked cryptographic signing overhead on a high-throughput C++ trading engine:
5 Golden Rules for Engineering Low-Latency Arbitrage Bots
ap-northeast-1): If trading Asian/Offshore exchanges (Binance, OKX, Bybit), hosting your server in Tokyo is mandatory.