Every novice crypto trader has experienced this tantalizing moment:
You open a market scanner and spot Ethereum trading at $3,400 on Binance and $3,468 on Kraken—a juicy +2.00% ($68 per ETH) price gap.
Your instincts tell you to buy 1 ETH on Binance, transfer it across the blockchain to Kraken, sell it for $3,468, and pocket an effortless $68 profit in 10 minutes.
You execute the trade. But when the dust settles, your balance has actually shrunk by -$12.40.
What went wrong? You fell into the Fixed Cost & Hidden Friction Trap:
Your $68 gross gain was obliterated by $80.40 in cumulative friction.
In this quantitative masterclass, we present the Ultimate Break-Even Arbitrage Calculator Engine, deconstruct the mathematical formulas for variable vs. fixed transaction drag, benchmark withdrawal costs across major blockchains, and dissect four real-world financial case studies.
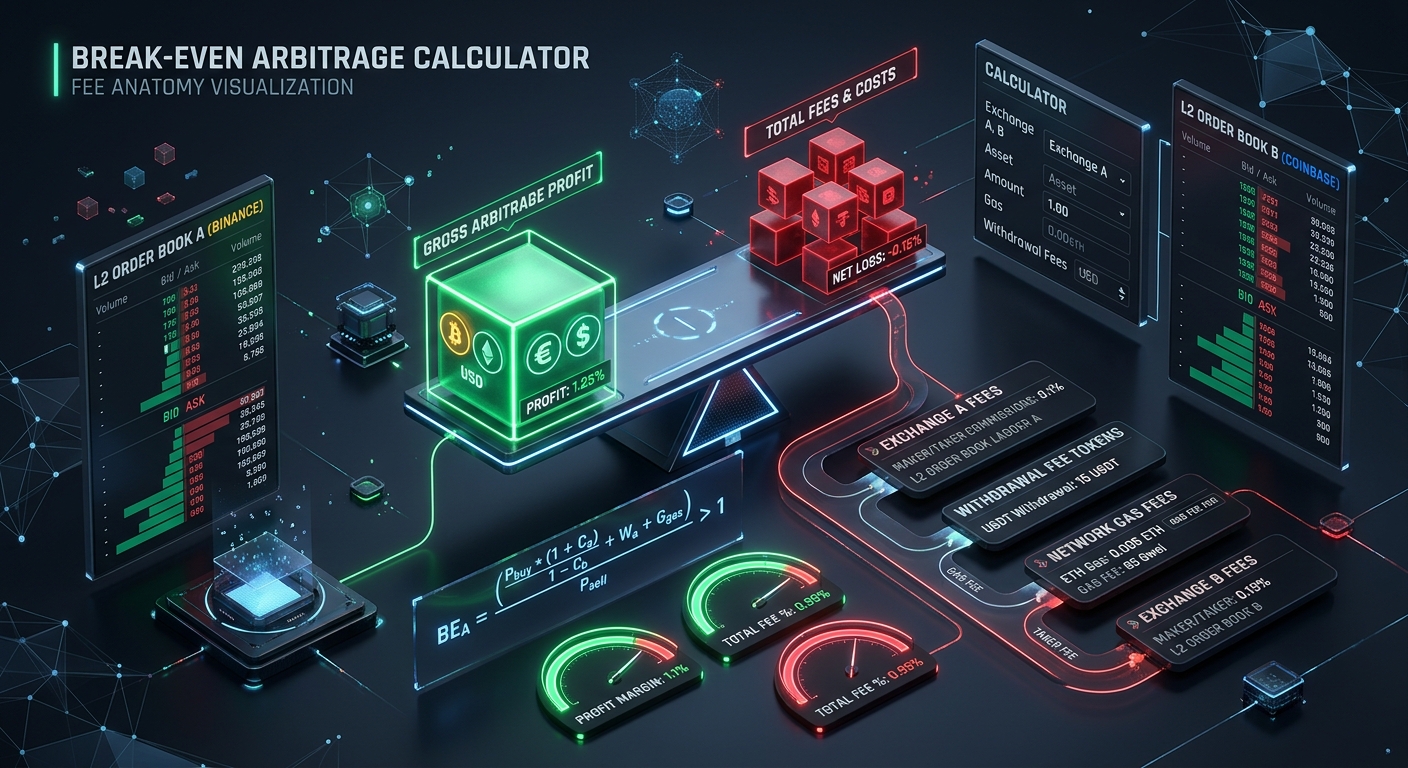
The Anatomy of Real Crypto Arbitrage Friction
[ GROSS ARBITRAGE SPREAD ]  <--- Must exceed total friction to generate profit
          |
          +---> 1. Variable % Commissions (Exchange A Taker Fee + Exchange B Maker/Taker Fee)
          +---> 2. Fixed Exchange Withdrawal Fee (Flat rate per crypto asset)
          +---> 3. On-Chain Network Gas Fees (L1/L2 smart contract execution costs)
          +---> 4. Bid-Ask Spread & Market Order Slippage (Level-2 order book depth impact)
          +---> 5. Transfer Volatility Drag (Price movement during blockchain confirmation time)
1. The Core Mathematical Break-Even Formulas
To determine whether a trade is mathematically viable before pressing "Buy", quantitative desks calculate three fundamental equations:
Formula 1: Total Realized Friction ($)
Total Friction = ≤ft(C × f_{buy}\right) + ≤ft(C × f_{sell}\right) + Fee_{withdrawal} + Fee_{gas} + ≤ft(C × Slippage_{%}\right)Where $C$ = Total Capital Deployed, $f_{\text{buy}}$ = Exchange A commission, $f_{\text{sell}}$ = Exchange B commission.
Formula 2: Minimum Required Break-Even Spread (%)
Spread_{break-even} (%) = ≤ft[(Fixed Withdrawal Fee + Network Gas Fee) / (Total Capital Deployed) + f_{buy} + f_{sell} + Slippage_{%}\right] × 100Formula 3: Minimum Profitable Capital (For a Given Spread)
If you identify an active +1.50% gross spread between two exchanges and your combined percentage fees + slippage equal 0.50% (leaving a 1.00% net buffer), what is the minimum trade size required to clear $25.00 in fixed withdrawal and gas fees?
Capital_{min} = (Total Fixed Fees ($)) / (Gross Spread (%) - Percentage Fees (%)) = ($25.00) / (0.0150 - 0.0050) = ($25.00) / (0.0100) = $2,500.00Any position smaller than $2,500 will result in a net financial loss, regardless of how wide the price gap appears on screen.
Fixed vs. Variable Friction Matrix Across Major Blockchains
| Settlement Blockchain / Network | Average CEX Withdrawal Fee ($) | On-Chain Transfer Gas ($) | Confirmation Time | Minimum Capital to Amortize Fixed Drag |
|---|---|---|---|---|
| Ethereum Mainnet (ERC-20) | $8.00 – $25.00 | $3.50 – $15.00 | 2 – 5 minutes | $10,000 – $25,000+ |
| Bitcoin Native (BTC) | $5.00 – $18.00 | $1.50 – $6.00 | 10 – 60 minutes | $15,000 – $30,000+ |
| Solana (SOL / SPL) | $0.05 – $0.50 | < $0.01 | 1 – 3 seconds | $250 – $500 |
| Arbitrum One / Optimism (L2) | $0.20 – $1.00 | $0.02 – $0.15 | 2 – 10 seconds | $500 – $1,000 |
| Base (Coinbase L2) | $0.15 – $0.80 | < $0.02 | 2 – 5 seconds | $300 – $800 |
| BNB Smart Chain (BEP-20) | $0.25 – $0.80 | $0.05 – $0.20 | 3 – 5 seconds | $500 – $1,000 |
| Tron (TRC-20 USDT) | $1.00 – $3.00 | $1.50 – $3.00 | 1 – 3 minutes | $1,500 – $3,000 |
Real-World Case Study 1: The Small Capital Illusion ($1,000 vs. $50,000 on ETH)
Consider an identical +2.50% ($85/ETH) gross price gap between Binance ($3,400) and Kraken ($3,485) tested across two different account sizes using on-chain spatial transfers:
| Fee / Parameter Breakdown | Trader A ($1,000 Capital) | Trader B ($50,000 Capital) |
|---|---|---|
| Starting Capital | $1,000.00 (0.2941 ETH) | $50,000.00 (14.7058 ETH) |
| Gross Spread (+2.50%) | +$25.00 | +$1,250.00 |
| Binance Taker Fee (0.10%) | -$1.00 | -$50.00 |
| Binance Fixed ETH Withdrawal | -$12.00 (Fixed flat fee) | -$12.00 (Fixed flat fee) |
| Ethereum Gas Fee (Transfer) | -$8.50 (Fixed flat fee) | -$8.50 (Fixed flat fee) |
| Kraken Taker Fee (0.26%) | -$2.60 | -$130.00 |
| Level-2 Order Book Slippage | -$0.50 (0.05%) | -$75.00 (0.15% depth sweep) |
| Total Friction Deducted | -$24.60 (2.46% drag) | -$275.50 (0.55% drag) |
| Net Realized Profit / (Loss) | +$0.40 (+0.04% Net) | +$974.50 (+1.95% Net Profit) |
The Financial Takeaway: Because fixed withdrawal ($12) and gas ($8.50) represented 2.05% of Trader A’s capital, their profit was completely wiped out. For Trader B, fixed fees represented a negligible 0.041% of capital, leaving +$974.50 in pure profit.
Real-World Case Study 2: The Solana High-Velocity Arbitrage ($5,000 on SOL)
A trader detected a +1.20% price gap on Solana between Bybit ($150.00) and Coinbase ($151.80):
Because Solana’s fixed transport drag is under $2.00, mid-sized accounts ($2,000–$5,000) can profitably harvest even tight 1% spreads.
Real-World Case Study 3: The Pre-Funded Dual-Balance Setup ($0 Gas, 0 Withdrawal Fees)
Professional quantitative desks completely bypass blockchain gas and exchange withdrawal fees by holding split balances on both venues:
At the end of the trading week, the desk conducts a single bulk rebalance transaction on a low-cost network, amortizing one fixed transfer fee across dozens of profitable trades.
Real-World Case Study 4: The DEX-to-CEX Gas Spike Trap ($5,000 on Uniswap v3)
A trader spotted an on-chain token trading at $10.00 on Uniswap (Ethereum L1) and $10.80 (+8.0%) on MEXC: