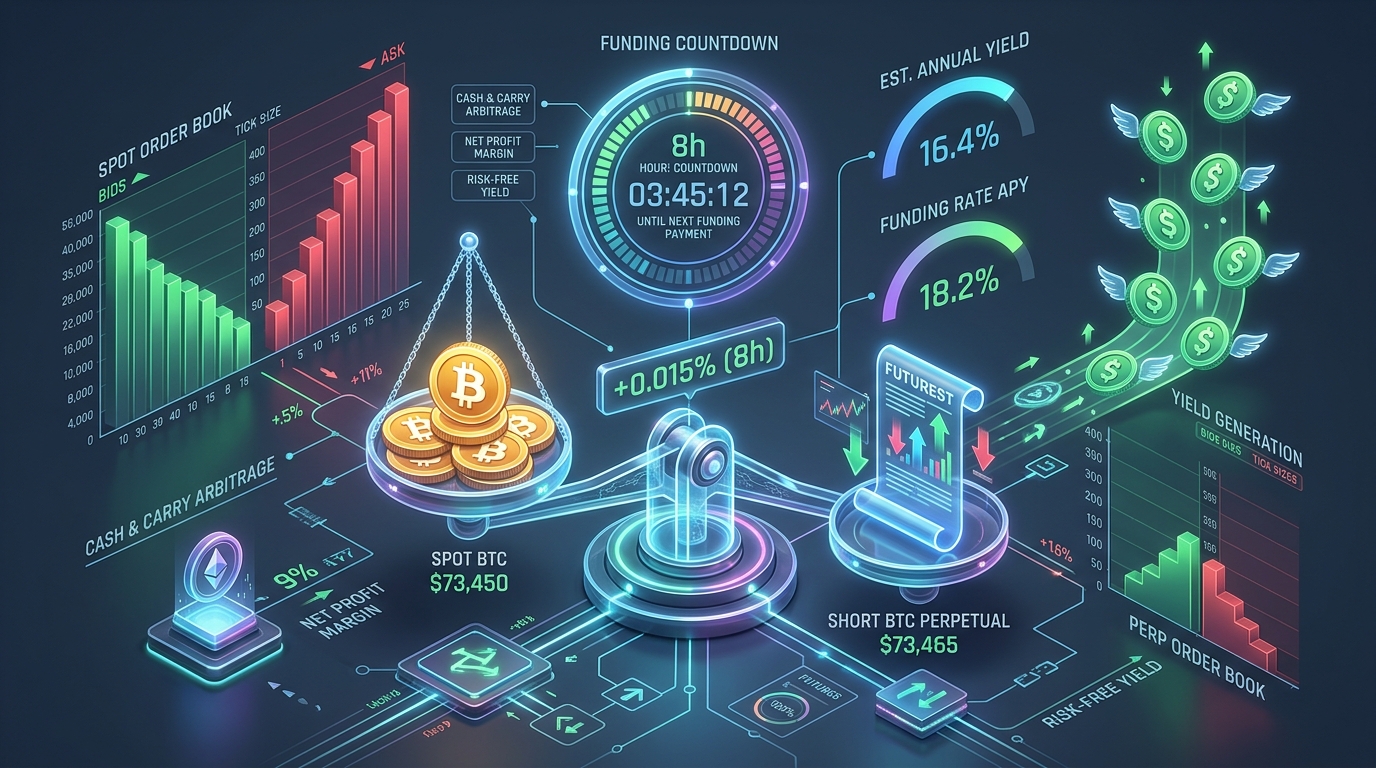
In traditional finance, hedge funds generate billions of dollars each year through delta-neutral cash-and-carry basis trades. In the cryptocurrency market, this concept is supercharged by the unique mechanics of Perpetual Futures Contracts (Perps). Because crypto perpetual contracts have no expiration date, exchanges use a periodic mechanism called the Funding Rate to tether the perpetual contract price to the underlying spot index price. When the market is bullish and leverage demand is overwhelmingly long, perpetual prices trade at a premium to spot. To re-anchor the market, long traders are forced to pay funding fees directly to short traders every 8 hours. By holding a long spot position while simultaneously holding an equal short perpetual position, you create a Delta-Neutral portfolio: whether Bitcoin doubles to $150,000 or crashes by 50%, your portfolio value remains completely protected, while you harvest recurring cash payments directly into your account. In this quantitative masterclass, we break down the mathematics of crypto funding rate arbitrage, walk through exact calculator formulas, evaluate cross-exchange perp-to-perp strategies, and analyze four real-world numerical case studies.
Perpetual Funding Rate Dynamics: How the Cash Flows Work
| Market Condition | Perpetual Price vs. Spot Index | 8-Hour Funding Rate | Payer $\rightarrow$ Receiver | Delta-Neutral Trade Strategy |
|---|---|---|---|---|
| Strong Bull Market | Perp trades at high premium | Positive (+0.03% to +0.15%) | Longs pay Shorts | Spot Long + Perp Short (Harvest Funding) |
| Baseline / Neutral | Perp trades near spot | Baseline (+0.0100% / 10.95% APR) | Longs pay Shorts | Spot Long + Perp Short (Baseline Yield) |
| Extreme Bear / Panic | Perp trades at discount | Negative (-0.03% to -0.20%) | Shorts pay Longs | Perp Long + Spot Short / Reverse Arb |
| Cross-Exchange Dislocation | Exchange A funding > Exchange B | Spread: +0.05% to +0.10% | Cross-exchange flow | Long Perp on A + Short Perp on B |
1. The Core Mathematical Formulas & Calculation Engine
Before deploying capital, quantitative traders calculate four vital metrics:
Formula 1: Periodic 8-Hour Cash Flow
Cash Flow per 8-Hour Cycle = Nominal Position Size × Funding Rate
Example: A $100,000 short position with a +0.05% funding rate receives $50.00 every 8 hours ($150.00/day).
Formula 2: Annualized Percentage Rate (APR)
APR = Funding Rate × 3 cycles/day × 365 days = Funding Rate × 1,095
Example: A funding rate of +0.03% per 8 hours translates to: $0.03\% × 1,095 = 32.85\% \text{ APR}$
Formula 3: Annualized Percentage Yield (APY with Auto-Compounding)
APY = ≤ft(1 + Funding Rate\right)^{1095} - 1
Example: For a +0.03% funding rate compounded 3x daily: $(1 + 0.0003)^{1095} - 1 = 38.89\% \text{ APY}$
Formula 4: Break-Even Horizon (Fee Amortization)
To enter and exit the trade, you must pay commissions across four transactions: (1) Buy Spot, (2) Short Perp, (3) Sell Spot, and (4) Close Perp.
Total Round-Trip Friction = Spot Entry Fee + Perp Entry Fee + Spot Exit Fee + Perp Exit Fee + Slippage
Break-Even Days = (Total Round-Trip Friction (%)) / (Daily Funding Rate (%))
If round-trip execution costs total 0.20% and daily funding yield is 0.06% (3x 0.02%), the position reaches pure profit on Day 3.33.
2. Strategy Architecture: Spot-Perp vs. Perp-Perp Arbitrage
Strategy Architecture A: Classic Spot-and-Perp Cash-and-Carry
- Capital Allocation: Divide capital into two equal halves (e.g. $50,000 USD on Spot and $50,000 USDT on Futures).
- Spot Purchase: Buy $50,000 worth of BTC at spot price ($65,000). You hold 0.7692 BTC.
- Futures Short: Open a 1x Short BTC/USDT Perpetual contract for 0.7692 BTC ($50,000 notional value).
- Portfolio State: Net Delta = 0. If BTC goes up 20%, your spot gains $10,000 and your futures loses $10,000. Every 8 hours, your futures account receives the funding payment in USDT.
Strategy Architecture B: Cross-Exchange Perp-Perp Spread Arbitrage
Occasionally, high-leverage retail exchanges (like Bybit or Bitget) exhibit much higher funding rates than institutional venues (like Binance or OKX):
- Bybit PEPE Perp Funding: +0.120% per 8 hours.
- Binance PEPE Perp Funding: +0.030% per 8 hours.
- Execution: Open Long Perp on Binance (pay 0.03%) and open Short Perp on Bybit (receive 0.12%).
- Net Yield: Capture the +0.090% net spread per cycle (98.5% annualized) without touching spot order books.
Real-World Case Study 1: The $100,000 Bitcoin Cash-and-Carry (30-Day Bull Run)
During a sustained Bitcoin rally from $60,000 to $72,000, funding rates averaged +0.028% per 8 hours across 30 days:
| Trade Parameter | Spot Leg | Perpetual Short Leg | Combined Portfolio |
|---|---|---|---|
| Starting Capital | $50,000.00 (Bought 0.8333 BTC at $60,000) | $50,000.00 (Short 0.8333 BTC 1x) | $100,000.00 Total |
| Trading Fees (Entry) | 0.075% Spot Maker ($37.50) | 0.020% Perp Maker ($10.00) | -$47.50 initial friction |
| 30-Day Market Price Move | BTC rose from $60,000 to $72,000 (+20%) | BTC short lost 20% | Net Price Impact: $0.00 |
| Funding Payments Received | $0.00 | 90 cycles $×$ avg $15.50 / cycle | +$1,395.00 cash |
| Trading Fees (Exit) | 0.075% Spot Maker ($45.00) | 0.020% Perp Maker ($12.00) | -$57.00 exit friction |
| Net Portfolio Value | $60,000.00 spot value | $41,281.00 margin balance | $101,290.50 Net Equity |
| Net Realized Return | — | — | +1.29% in 30 Days (15.7% Net APR) |
The Quantitative Lesson: Despite wild 20% price swings, the trader extracted a completely risk-free +$1,290.50 cash profit with zero drawdowns.
Real-World Case Study 2: The Ethena / Altcoin Funding Rate Mania ($50,000 Test)
During an explosive altcoin rally on Solana (SOL), funding rates spiked to +0.115% per 8 hours (+0.345% per day / 125.9% APR):
- Capital Allocated: $25,000 Spot SOL + $25,000 Short SOL/USDT Perp.
- Daily Cash Flow: $25,000 $×$ 0.345% = +$86.25 per day.
- Break-Even Point: Round-trip maker fees ($25,000 $×$ 0.15% = $37.50) were recouped in 10.4 hours.
- 7-Day Total Yield: +$603.75 net cash collected in one week (+1.21% on total capital).
Real-World Case Study 3: Cross-Exchange Perp-to-Perp Spread Arbitrage
An automated market maker spotted a persistent funding rate dislocation on DOGE/USDT:
- Bybit DOGE Perp Funding: +0.085% per 8h.
- OKX DOGE Perp Funding: +0.015% per 8h.
- Net Funding Spread: +0.070% per 8h (0.210%/day).
Execution on $50,000 Notional ($25,000 Margin at 2x Leverage):
- Opened Long 500,000 DOGE on OKX at $0.1500 ($25,000 collateral).
- Opened Short 500,000 DOGE on Bybit at $0.1500 ($25,000 collateral).
- Daily Net Funding Harvest: $75,000 notional $×$ 0.210% = +$157.50 / day.
- Net 14-Day Yield: +$2,110.00 after all maker commissions (+8.44% on collateral in two weeks).
Real-World Case Study 4: The Parabolic Pump Margin Liquidation Trap (Risk Analysis)
A trader attempted funding rate arbitrage on a trending low-cap token without understanding liquidation mechanics:
- Capital: $10,000 Spot + $10,000 Futures Margin (3x Short Leverage = $30,000 notional).
- The Black Swan: The token unexpectedly rallied +42% in 3 hours.
- The Flaw: The spot position gained +$4,200, but the 3x leveraged short futures leg hit its Liquidation Price, wiping out the $10,000 futures margin.
- The Disaster: After getting liquidated on the short leg, the token immediately crashed -30% over the next 6 hours, destroying the remaining spot value.
- The Golden Rule of Funding Arbitrage: Never use more than 1x to 2x leverage on the short leg, and always use Cross-Margin or auto-margin top-ups to prevent premature liquidation.
The 5 Essential Rules for Safe Funding Rate Arbitrage
- Use 1x Leverage by Default: A 1:1 spot-to-short hedge eliminates liquidation risk completely if isolated margin is backed 100% by cash.
- Monitor Funding Rate Sign Flips: If a bear market pushes funding rates negative (<0.00%), close the position immediately to avoid paying fees to stay in the trade.
- Always Use Maker Orders: Taker fees (0.05% to 0.075%) can eat 3 to 5 days of funding income. Use resting Post-Only limit orders on both legs.
- Account for Basis Premium: When entering, check if the perp is trading higher than spot (Contango). Selling the perp at a premium locks in extra basis yield upon convergence.
- Diversify Across Tier-1 Venues: Spread capital across Binance, Bybit, OKX, and Kraken to mitigate exchange counterparty and withdrawal risks.