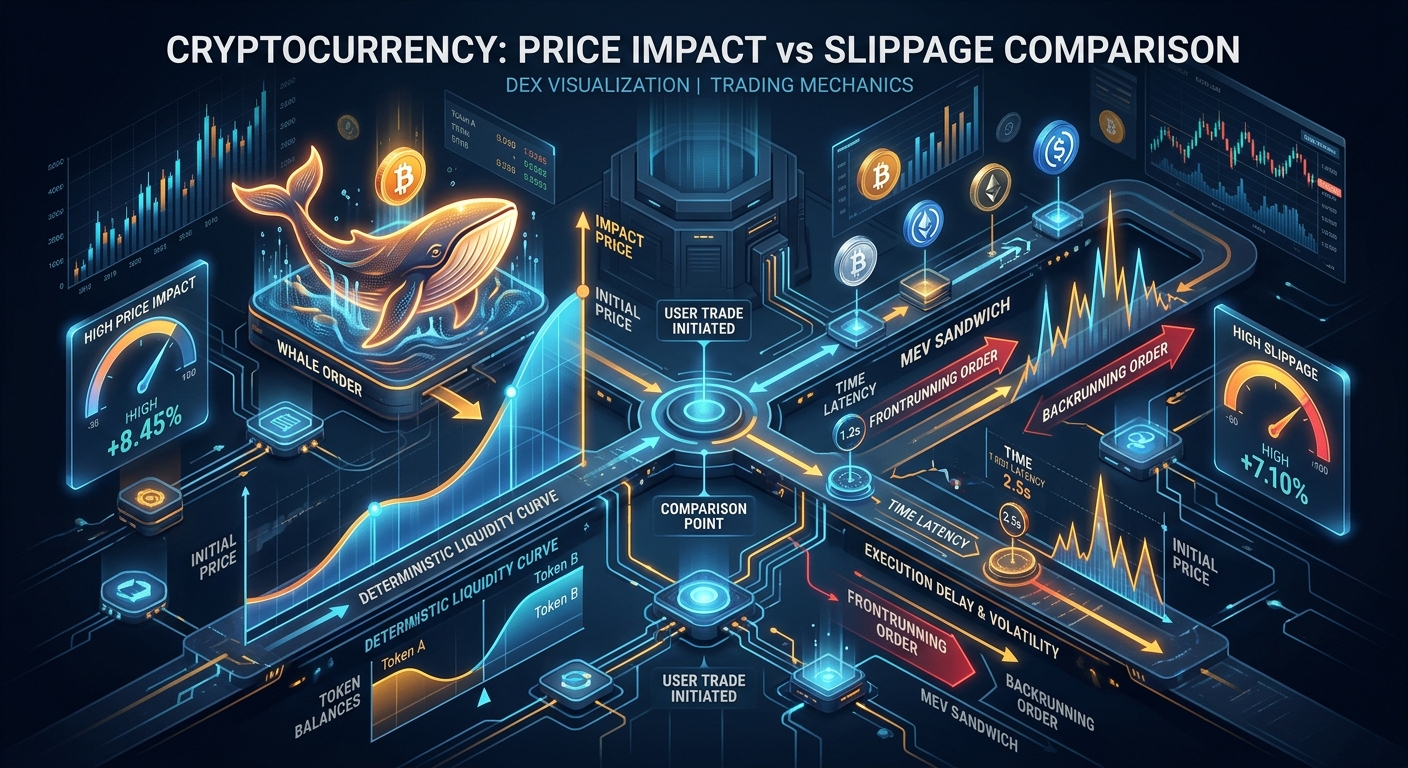
In decentralized finance (DeFi) and centralized cryptocurrency exchanges, few concepts are more frequently confused than Price Impact and Slippage.
Traders regularly use them as interchangeable buzzwords:
“I lost 6% on my swap because of slippage!”
“The DEX warned me about a 12% price impact, so I adjusted my slippage tolerance to 12%!”
Conflating these two distinct market mechanics is one of the fastest ways to lose thousands of dollars in execution drag, trigger catastrophic trades on illiquid DEX pools, and fall victim to predatory Maximal Extractable Value (MEV) sandwich bots.
While both forces degrade your final execution price, they stem from fundamentally different economic causes, operate on different timelines, and require completely different risk management strategies.
In this quantitative execution masterclass, we will demystify the exact difference between Price Impact and Slippage, explain the underlying mathematics behind Automated Market Maker (AMM) liquidity curves and Level-2 order book depth, provide a comparative benchmark matrix, and dissect four real-world financial case studies.
The Core Conceptual Difference: The Cannonball vs. The Wave
To build an intuitive, unforgettable mental model, consider the difference between jumping into a swimming pool and swimming in an ocean current:
[ PRICE IMPACT: THE CANNONBALL ]                    [ SLIPPAGE: THE OCEAN CURRENT ]

  Cause: YOUR OWN WEIGHT (Order Size)                Cause: EXTERNAL WAVES (Market Movement & Time)
  - You jump into a small pool (thin liquidity).     - You stand on the shore looking at a calm spot.
  - Your body directly displaces the water level.     - Before you can dive, a rogue wave rolls in.
  - The water rises solely because of YOUR action.   - The water level changed because of OTHERS.
- 100% PREDICTABLE before jumping. - UNPREDICTABLE until you hit the water.| Feature / Parameter | Price Impact | Slippage |
|---|---|---|
| Primary Cause | Your own order size relative to pool/book liquidity | Market price movement & competing transactions during execution delay |
| Who Causes It? | You (the trader executing the order) | Other market participants, bots, and network latency |
| Predictability | 100% Deterministic (calculated precisely before you click) | Probabilistic / Dynamic (unknown until block inclusion or fill) |
| Time Component | Static snapshot at the microsecond of order initiation | Time-dependent (grows with blockchain confirmation lag or network congestion) |
| Where It Happens | Both DEX Automated Market Makers (AMMs) & CEX Order Books | Both DEX Swaps & CEX Market Orders |
| Protection Method | Slicing order size (TWAP), using DEX aggregators, deep liquidity | Setting strict Slippage Tolerance (0.1%–0.5%), using private RPC endpoints (Flashbots) |
1. The Anatomy of Price Impact: How Your Order Shifts the Market
Price Impact is the instantaneous, deterministic price change caused by the size of your own transaction relative to the total available liquidity.
On Automated Market Makers (DEXs like Uniswap, Sushiswap, Raydium):
Most decentralized exchanges operate on the Constant Product Market Maker (CPMM) invariant formula:
x × y = kWhere $x$ is the reserve of Token A, $y$ is the reserve of Token B, and $k$ is a fixed invariant constant.
When you deposit a large amount of Token A to buy Token B, the ratio of tokens in the pool changes immediately. Because the invariant $k$ must remain constant, the marginal price of Token B increases exponentially as pool reserves are drained.
The Mathematical Price Impact Formula (AMM):
Price Impact (%) = |1 - \frac{P_{marginal}}{P_{effective}}| × 100 = (Δ x) / (x + Δ x) × 100For example: If a pool contains 100 ETH ($x$) and 340,000 USDC ($y$), and you swap 10 ETH ($Δ x = 10$), your trade represents $\frac{10}{100 + 10} = 9.09\%$ of the updated pool, creating a ~9.09% Price Impact before any external market changes occur.
On Centralized Exchanges (CEXs like Binance, Coinbase):
On an order book exchange, Price Impact occurs when your market buy order is larger than the quantity resting at the Best Ask (Top-of-Book). Your order must "sweep the book," pushing the market price up to the next available limit order.
2. The Anatomy of Slippage: How Time and Competition Erode Your Fill
Slippage is the difference between the price you expected to pay when you pressed the "Swap" or "Buy" button and the actual execution price at which your transaction was finalized.
Slippage is caused by the time delay between transaction broadcast and final execution:
The Mathematical Slippage Formula:
Slippage (%) = |\frac{P_{executed} - P_{expected}}{P_{expected}}| × 100Positive vs. Negative Slippage:
3. The Dangerous Trap: Slippage Tolerance is NOT Price Impact Tolerance
One of the most dangerous misconceptions in crypto UI design is the Slippage Tolerance Setting (e.g. 0.5%, 1%, 5%).
Many traders see a high Price Impact warning (e.g., "Warning: High Price Impact of 8.5%") and believe that increasing their Slippage Tolerance to 10% will "fix" the issue.
Why This is Catastrophic:
If you have an 8% Price Impact and set your Slippage Tolerance to 10%, you are telling the blockchain: “I am already paying an 8% premium for my trade size, and I am willing to lose an ADDITIONAL 10% on top of that if someone frontruns me!”
This creates a massive target for MEV Sandwich Bots.
[ THE ANATOMY OF AN MEV SANDWICH ATTACK ]

  1. FRONTRUN (MEV Bot Buy): Bot spots your pending tx with 5% slippage tolerance in mempool.
     - Bot bribes miner with high priority fee to execute a BUY order right BEFORE you.
     - Pushes price up by exactly 4.99%.

  2. VICTIM SWAP (Your Trade): Your trade executes at the worst allowable price limit.
     - You fill near your max slippage tolerance ceiling.

  3. BACKRUN (MEV Bot Sell): Bot executes an immediate SELL order right AFTER you.
     - Bot dumps the tokens at the inflated price, pocketing guaranteed risk-free profit from YOUR wallet.
Quantitative Benchmark Matrix: Price Impact vs. Slippage Dynamics
| Scenario / Trading Condition | Typical Price Impact | Typical Market Slippage | Total Execution Cost | Primary Driver |
|---|---|---|---|---|
| $1,000 Trade on Deep CEX (BTC/USDT) | < 0.001% | < 0.005% | ~0.005% ($0.05) | Perfect execution efficiency |
| $50,000 Trade on Deep CEX (BTC/USDT) | ~0.010% | ~0.015% | ~0.025% ($12.50) | Deep Level-2 order book depth |
| $50,000 Trade on Mid-Cap Altcoin CEX | 1.80% – 3.50% | 0.20% – 0.80% | 2.00% – 4.30% ($1,500+) | Thin order book walking the book |
| $10,000 Swap on High-Liquidity DEX ($100M TVL) | ~0.020% | 0.05% – 0.15% | ~0.10% ($10.00) | Deep concentrated liquidity pool |
| $10,000 Swap on Low-Cap DEX ($80k TVL) | 11.10% | 0.50% – 3.00% | 11.60% – 14.10% ($1,250+) | AMM reserve depletion curve ($x · y = k$) |
| Trading during High-Volatility News Event | 0.050% | 3.00% – 8.00%+ | 3.05% – 8.05% ($800+) | High mempool congestion & fast price drift |
Real-World Case Study 1: The $100,000 Altcoin Swap on Uniswap v2 (12.5% Price Impact, 0% Slippage)
A trader held $100,000 of USDC and wanted to buy a trending DeFi governance token on Uniswap v2:
The loss was 100% driven by Price Impact, despite slippage being literally zero.
Real-World Case Study 2: The Fast-Breakout Momentum Buy (0.05% Price Impact, 4.2% Negative Slippage)
During a sudden macroeconomic announcement (such as a Federal Reserve rate cut), Bitcoin began breaking out:
The trader suffered a severe execution penalty caused 100% by Slippage (market latency drift), while Price Impact was practically non-existent.
Real-World Case Study 3: The 8% Slippage Tolerance Disaster (The $14,000 MEV Sandwich)
A crypto investor wanted to purchase $200,000 of a newly launched Layer-2 token on an Ethereum DEX:
The Quantitative Lesson: Never increase slippage tolerance to compensate for high price impact. Use private RPC endpoints (like Flashbots Protect) or DEX aggregators.
Real-World Case Study 4: Arbitrage Execution Disaster (Confusing Price Impact with Capacity)
An arbitrage scanner detected a +5.00% gross price difference on a token between Uniswap ($10.00) and Sushiswap ($10.50):
The arbitrageur assumed the 5% price gap applied to the entire $50,000 capital, failing to calculate that the sell-side Price Impact would completely obliterate the spread.