It is every crypto investor’s worst nightmare—and one of the most expensive rookie mistakes in quantitative finance:
You are sitting on a massive winning position. Perhaps you accumulated $250,000 worth of a mid-cap altcoin, or you need to liquidate 50 Bitcoin to reallocate capital.
You open your exchange dashboard, choose your full balance, and smash the "Market Sell" button.
Three seconds later, you check your USDT balance and freeze:
Your $250,000 position only yielded $212,000.
You didn’t pay a massive trading fee. You weren’t hacked. You inflicted self-sabotaged slippage on your own trade by single-handedly consuming every bid in the order book, creating a personal flash crash.
In this comprehensive institutional execution guide, we break down the mechanics of order book impact, identify the optimal global time windows for maximum liquidity, and share the algorithmic execution strategies that hedge funds and crypto whales use to offload multi-million-dollar positions completely undetected.
1. The Anatomy of Market Impact: How Order Books Actually Work
The price you see flashing in green and red on your exchange screen is merely the Top-of-Book (Best Bid / Best Ask).
It only represents the price for the tiny quantity of coins sitting at the very first order book level (often just $500 to $5,000 worth of liquidity).
[ THE ORDER BOOK SWEEP PHENOMENON ]

  TOP OF BOOK (Deceptive): ETH @ $3,500.00 (Only 1.5 ETH available!)

  Incoming Large Market Sell: 100 ETH ($350,000 nominal value)
  ─────────────────────────────────────────────────────────────────
  Level 1:  1.5 ETH  sold @ $3,500.00  ──►  $5,250.00
  Level 2:  4.0 ETH  sold @ $3,492.00  ──►  $13,968.00
  Level 3:  8.5 ETH  sold @ $3,475.00  ──►  $29,537.50
  Level 4: 15.0 ETH  sold @ $3,440.00  ──►  $51,600.00
  Level 5: 35.0 ETH  sold @ $3,380.00  ──►  $118,300.00
  Level 6: 36.0 ETH  sold @ $3,210.00  ──►  $115,560.00 (DEEP CRASH!)
  ─────────────────────────────────────────────────────────────────
  Total Realized:    $334,215.50 (Average Price: $3,342.15)
  NET VALUE DESTROYED (SLIPPAGE): -$15,784.50 (-4.51% Self-Inflicted Loss!)
When your order size exceeds the top bid, the matching engine automatically moves down the ladder, executing remaining chunks against lower and lower bids until the order is filled.
Worse still, algorithmic High-Frequency Trading (HFT) market makers instantly detect large market sells, immediately cancel their existing bid quotes, and re-post them 2% lower, widening the spread in microseconds.
2. The 3 Golden Rules of Execution Timing
Liquidity in cryptocurrency is not constant—it breathes in predictable, cyclical tidal waves throughout the 24-hour day:
[ GLOBAL CRYPTO LIQUIDITY CLOCK ]

  00:00 UTC                 08:00 UTC                 13:00 - 16:00 UTC           20:00 UTC
  ┌─────────────────────────┬─────────────────────────┬───────────────────────────┬──────────────┐
  │ Asian Open & Perp       │ European Morning        │ LONDON & NEW YORK OVERLAP │ US Afternoon │
  │ Funding Rate Settlement │ Session                 │ (PEAK GLOBAL LIQUIDITY)   │ Retail Fade  │
  │ (Moderate Depth)        │ (Steady Volume)         │ (4x Deeper Bid Books)     │ (Thin Books) │
  └─────────────────────────┴─────────────────────────┴───────────────────────────┴──────────────┘
Rule 1: Trade During the London / New York Overlap (13:00 to 16:00 UTC)
The single deepest liquidity window in global crypto markets occurs when European financial centers (London, Frankfurt) and North American institutions (New York, Chicago) are both actively trading.
During these three hours, institutional market makers (Wintermute, Jane Street, Jump) provide their tightest spreads and deepest cumulative order books.
Executing a $500k sell during the overlap produces up to 75% less slippage than executing the exact same order during Asian weekend hours.
Rule 2: Exploit Funding Rate Rebalancing Surges (00:00, 08:00, 16:00 UTC)
Perpetual futures contracts settle funding rates every 8 hours. When market sentiment is overwhelmingly bullish (positive funding rates), long traders pay short traders a hefty yield.
Institutional basis traders continuously purchase spot crypto to hedge short perpetual futures positions immediately before funding snapshots, creating a temporary surge of aggressive spot buy volume that easily absorbs large sell blocks.
Rule 3: Avoid the "Dead Zone" (Sunday Asian Night: 02:00 – 06:00 UTC)
Sunday night in Asia is notoriously the thinnest, most illiquid period of the week. Traditional banks are closed, institutional market makers pull their capital off the order books to reduce weekend risk, and trading volumes drop by 60%.
Never execute a large market sell on a Sunday evening unless you are facing an emergency solvency event.
3. Algorithmic Execution Strategies: The Whale Playbook
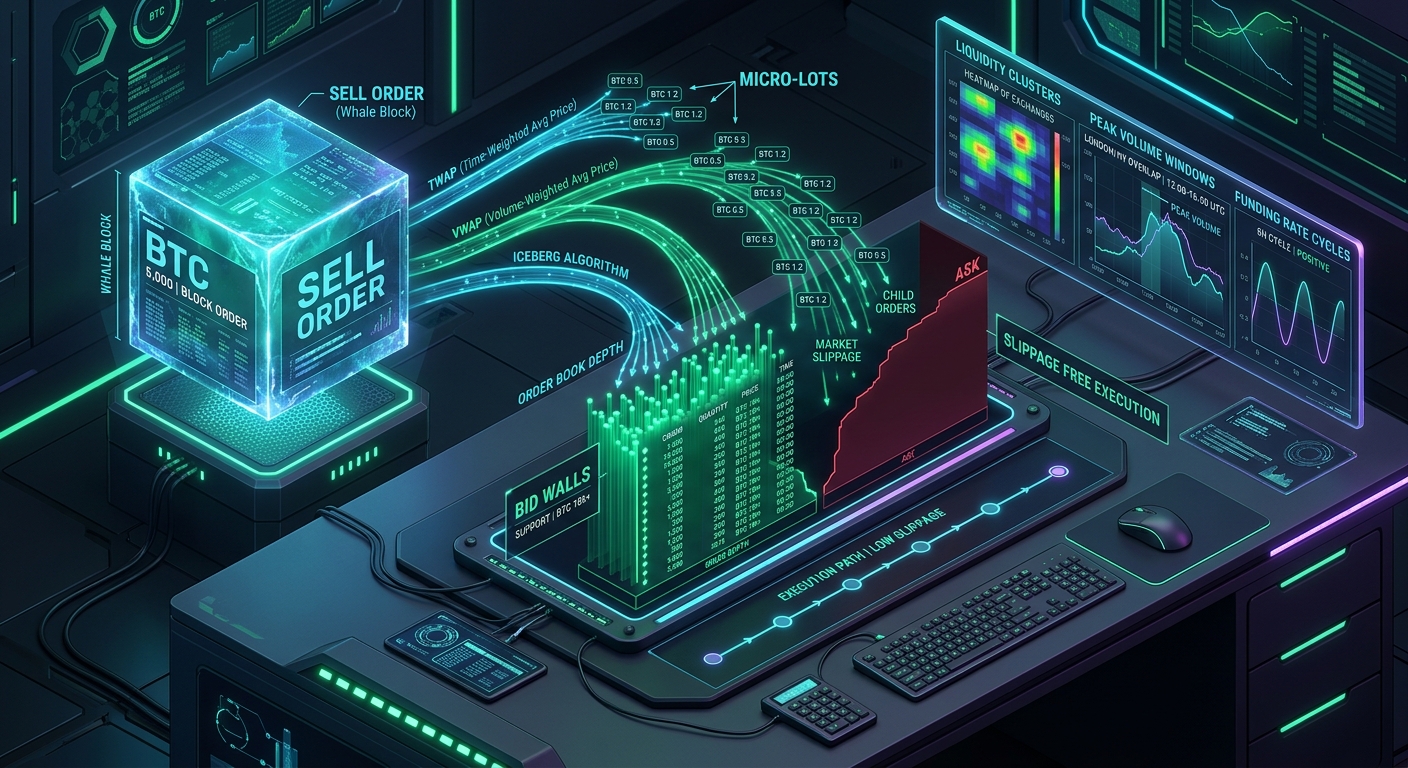
Professional quantitative trading desks never dump positions in a single order. Instead, they deploy automated execution algorithms:
[ INSTITUTIONAL EXECUTION TOOLKIT ]

  1. TWAP (Time-Weighted Average Price)  ──► Slices order into equal micro-lots over time
  2. VWAP (Volume-Weighted Average Price) ──► Matches historical volume curve to minimize footprint
  3. ICEBERG ORDERS                     ──► Displays only 2-5% of total order size on public order book
  4. OTC DESKS & DARK POOLS              ──► Direct bilateral trade matching with zero public book impact
  5. CoW SWAP & PRIVATE RPCs (DEX)      ──► Batch auctions & Flashbots Protect to block MEV sandwich bots
1. Time-Weighted Average Price (TWAP)
A TWAP algorithm divides a large order into small, randomized child orders executed at regular time intervals (e.g., selling $2,500 every 90 seconds over a 4-hour window).
This allows organic market maker replenishment algorithms to refill the top-of-book bids between child orders, keeping average realized execution price within 0.05% of fair market value.
2. Volume-Weighted Average Price (VWAP)
Unlike TWAP (which trades evenly across time), VWAP dynamically adjusts trade sizing based on historical volume patterns. It sells aggressively during high-volume hours (14:00 UTC) and scales back during low-volume lulls (04:00 UTC).
3. Iceberg Orders
An Iceberg order places a large limit sell on the exchange book, but only displays a fraction (e.g. 5%) to other traders.
If you want to sell 1,000 ETH at $3,500, the public order book only shows a sell wall of 50 ETH. As soon as buyers fill that 50 ETH, the exchange immediately regenerates another 50 ETH at the same price until the full 1,000 ETH is exhausted.
This prevents other market participants from panicking when they see a massive sell wall and front-running your exit.
4. CoW Swap Batch Auctions & Private RPCs (For On-Chain DEX Exits)
If you are selling tokens on decentralized exchanges (Uniswap, Raydium), a large public swap in the mempool will be instantly attacked by MEV sandwich bots.
To prevent this:
4. Over-The-Counter (OTC) Desks: When to Go Off-Exchange
If your position size exceeds 10% of the daily spot trading volume of an asset, public order books cannot absorb your trade without catastrophic price destruction.
In these scenarios, hedge funds utilize Institutional OTC Desks (such as Coinbase Prime, Wintermute, or FalconX):
| Feature | Public Centralized Exchange | Institutional OTC Desk |
|---|---|---|
| Best For | Positions < $250,000 | Positions > $500,000 – $50,000,000+ |
| Pricing Model | Variable execution (Subject to slippage) | Fixed, pre-negotiated strike price (RFQ) |
| Market Impact | High (Directly visible on public charts) | Zero (Transacted off-order-book) |
| Settlement | Immediate on-exchange balance | T+0 or T+1 bilateral wire/crypto settlement |
| Execution Method | Order book matching | Direct principal liquidity / dark pool |
5. High-Stakes Case Studies: The Cost of Impatience
Case Study 1: The Kraken Ethereum Flash Crash to $700 (Feb 2021)
During a mild crypto pullback in February 2021, a single whale initiated an un-hedged massive market sell of tens of thousands of ETH on Kraken spot markets.
The order annihilated the entire Level-2 bid book down to $700, while ETH was simultaneously trading at $1,600 on Binance and Coinbase.
The whale suffered an estimated $8,000,000+ in self-inflicted slippage losses in less than 45 seconds, while automated arbitrage bots scooped up discounted ETH at a 55% discount.
Case Study 2: The Stealth $50M Bitcoin OTC Unwind
In late 2024, an early crypto venture fund needed to distribute $50,000,000 in Bitcoin to limited partners.
Rather than dumping on Binance spot, the trading desk utilized an institutional Smart Order Router (SOR) combined with a 36-hour VWAP algorithm across six separate liquidity venues and two dark pools.
The average execution price differed from the starting mid-market price by less than 0.04%, saving over $1,800,000 in slippage compared to manual execution.
6. Quantitative Pre-Flight Execution Checklist
Before clicking sell on any large crypto position, run through this operational pre-flight checklist: