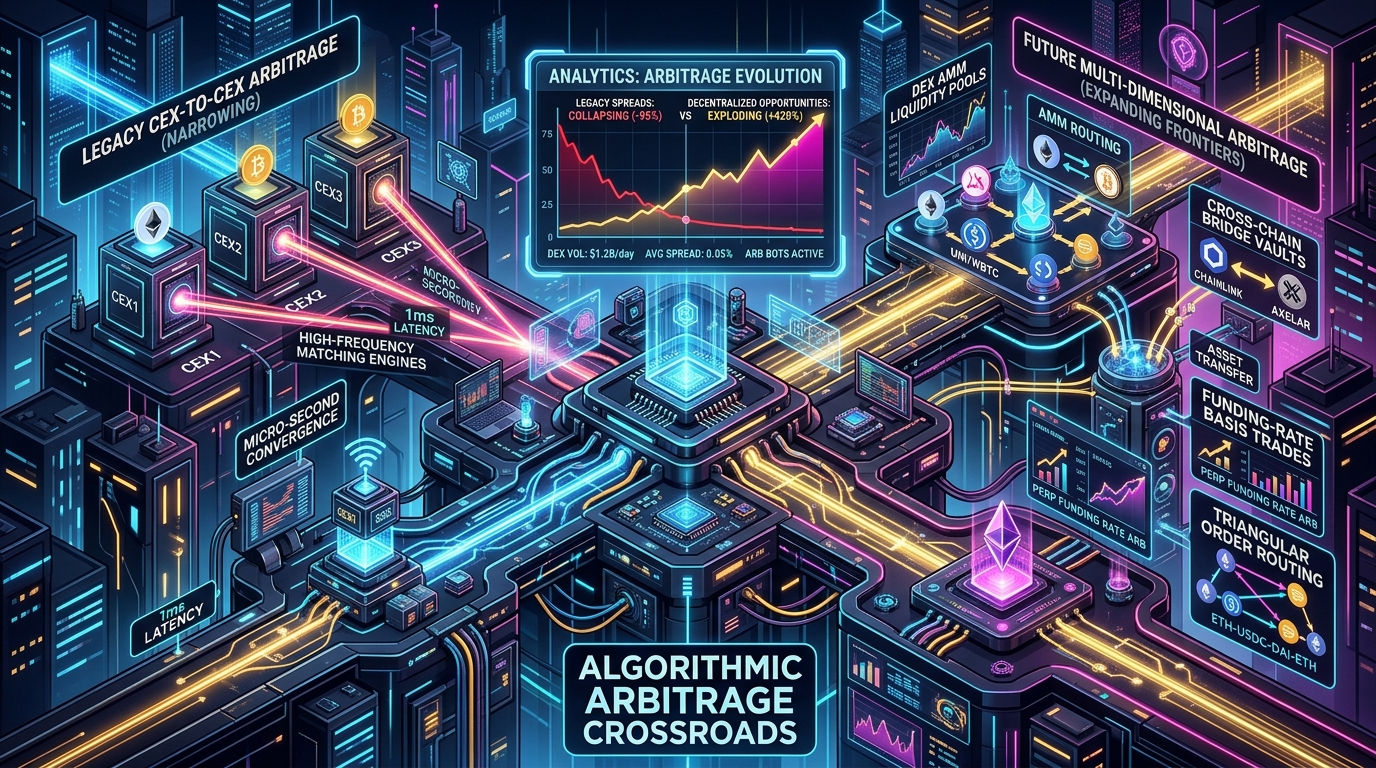
Every few months, a familiar eulogy echoes through crypto Twitter and quantitative trading forums:
"Arbitrage in crypto is dead. The institutions have arrived. Market makers with colocation in Dublin and Tokyo have squeezed spreads to zero. There are no free lunches left."
To anyone who traded cryptocurrency in 2017 or 2018, the contrast is undeniable.
Back then, you could open Bitstamp, buy Bitcoin for $8,000, send it over the blockchain while drinking a coffee, and sell it on GDAX (Coinbase) for $8,400. That +5.0% spread would sit open for hours, waiting for anyone with a verified bank account to collect risk-free profits.
Today, if Bitcoin’s price on Binance deviates by just 0.02% (2 basis points) from Coinbase, algorithmic bots execute thousands of cross-exchange trades and collapse the spread in less than 15 milliseconds.
So, is crypto arbitrage truly dying?
The short answer: No. Naive arbitrage is dead. Modern multi-dimensional arbitrage is bigger, richer, and more profitable than ever before.
In this deep-dive analysis, we explore what actually died, why price convergence occurs, and how the fragmentation of modern crypto infrastructure has created a multi-billion-dollar playground of structural arbitrage opportunities.
1. What Actually Died: The Era of "Lazy" Bilateral Arbitrage
To understand where the market is going, we must first understand why the old game disappeared.
[ THE EVOLUTION OF CRYPTO ARBITRAGE: 2017 vs. TODAY ]

  2017 "NAIVE" ARBITRAGE:                 TODAY'S "ALGORITHMIC" REALITY:
  • Execution Speed:   30 – 120 minutes    • Execution Speed:   2 – 50 milliseconds
  • Typical Spread:    2.0% – 8.0%         • Typical Spread:    0.01% – 0.05% (Major CEXs)
  • Infrastructure:    Manual web browser  • Infrastructure:    Direct FIX/WebSocket colocation
  • Capital Route:     On-chain transfers  • Capital Route:     Pre-funded balance netting & credit lines
  • Competition:       Retail hobbyists    • Competition:       Wintermute, Jump, Flow Traders
The death of simple bilateral spot arbitrage was driven by three irreversible structural forces:
2. The Paradox of Convergence: Why More Efficiency Creates More Opportunity
If centralized exchanges have become hyper-efficient, why hasn’t arbitrage vanished completely?
Because crypto is not a single, centralized stock exchange like the NYSE. Crypto is a hyper-fragmented, permissionless financial universe that expands faster than market makers can homogenize it.
[ THE CRYPTO LIQUIDITY FRAGMENTATION TREE ]

                       CENTRALIZED VENUES (CEXs)
                     (Binance, Coinbase, Bybit, OKX)
                                   │
            ┌──────────────────────┴──────────────────────┐
            ▼                                             ▼
    DECENTRALIZED EXCHANGES (DEXs)               DERIVATIVES & SYNTHETICS
    (Uniswap, Curve, Raydium, Aerodrome)         (Perpetual Futures, Basis Trades)
            │                                             │
    ┌───────┴───────┐                             ┌───────┴───────┐
    ▼               ▼                             ▼               ▼
  EVM Layer-2s   Alt-L1 Chains                 Funding Rate     Wrapped / LST
 (Base, Arbitrum)(Solana, Sui)                 Cash & Carry       De-pegs
Every time a new blockchain, Layer-2 rollup, perpetual DEX, or liquidity pool launches, a brand-new set of cross-market price discrepancies is born.
3. The 4 Thriving Frontiers of Modern Crypto Arbitrage
Traders who complain that arbitrage is dead are simply looking in the wrong place. Here is where quantitative alpha lives today:
Frontier 1: DEX-to-CEX Latency & Pool Imbalance Arbitrage
Frontier 2: Perpetual Futures Funding Rate Cash & Carry
Frontier 3: Cross-Chain Liquidity & Bridge Discrepancies
Frontier 4: Synthetic Asset & Wrapped Token Parity Divergence
4. Where the Retail & Semi-Pro Edge Resides Today
Can independent traders still compete against institutional HFT firms? Yes, by choosing the right battlefield:
[ WHERE TO COMPETE vs. WHERE TO AVOID ]

  ❌ AVOID (Guaranteed Loss to Institutional Bots):
  • Sub-millisecond BTC/USDT spot arbitrage between Binance and Bybit.
  • Front-running Ethereum mainnet mempool MEV bundles (PGA gas wars).
  • High-frequency colocation speed races.

  ✅ TARGET (High-Probability Structural Opportunities):
  • Altcoin cross-exchange spreads during regional market open/close hours.
  • Fiat banking premium arbitrage (Coinbase USD / Kraken EUR vs. offshore USDT).
  • Cross-venue synthetic and wrapped asset mean-reversion trades.
  • Multi-leg fee-rebate capture across maker/taker VIP tier programs.