Imagine walking into a grocery store to buy a dozen apples.
The price tag on the shelf reads $1.00 per apple.
You place twelve apples in your cart, walk up to the cash register, and the cashier says: "That will be $18.50, please."
Confused, you point at the shelf: "Wait, didn’t the label say $1.00 each?"
The cashier smirks and replies: "Oh, the first apple was $1.00. But the second apple was $1.15, the third was $1.40, the next four were $1.75, and the last five were $2.20 each because nobody else brought apples to the store today."
In everyday commerce, this would be considered outright highway robbery.
In cryptocurrency markets, this is what happens every single second on low-liquidity altcoins.
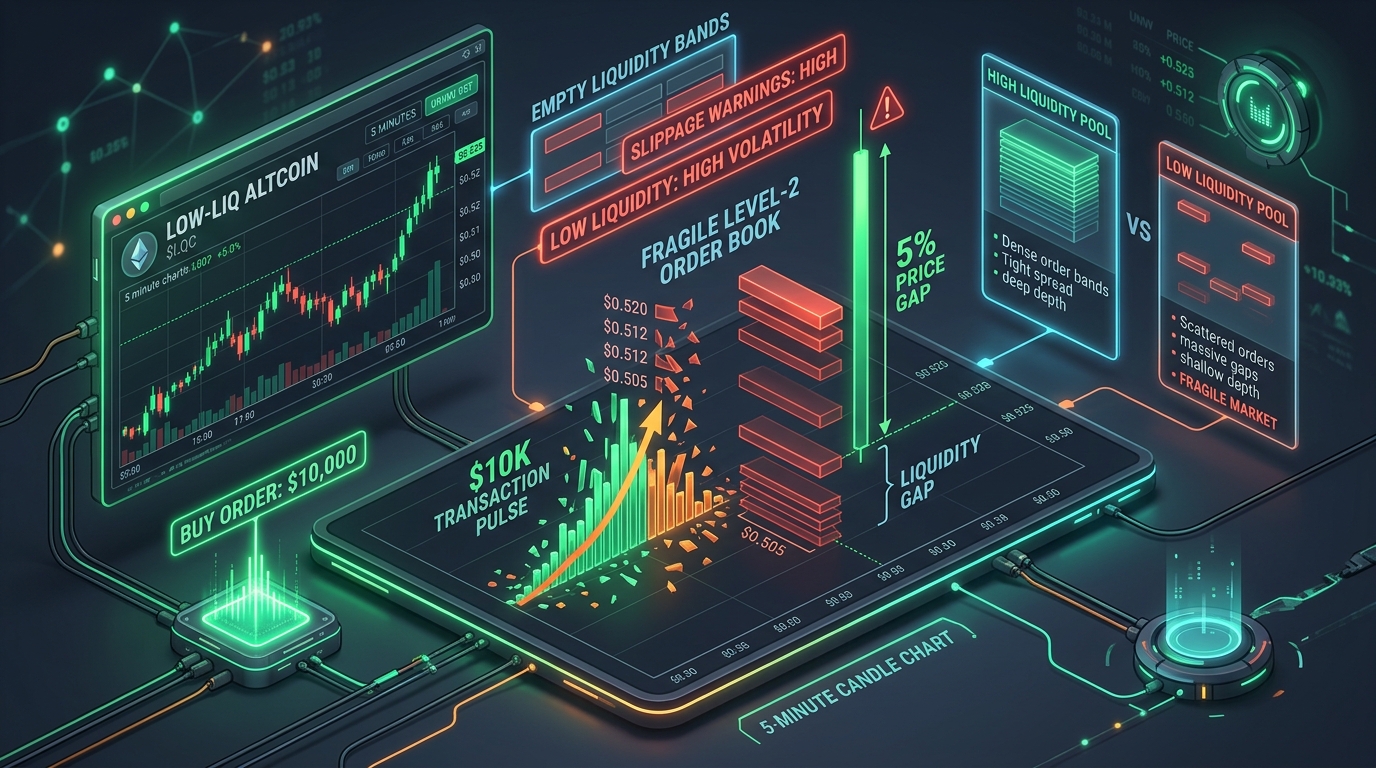
A trader sees a token with a $35,000,000 market cap and $1,200,000 in reported 24-hour volume. They click "Market Buy" for a modest $10,000. In less than two seconds, the 1-minute chart prints an aggressive +5.4% green wick, and the trader’s realized fill price is 4.8% higher than the mid-market price quoted on their screen.
Why does this happen? In this deep-dive guide, we examine the structural mechanics of illiquid order books, explore the phenomenon of "air pockets" (price gaps), dissect constant-product AMM pool math, and provide actionable rules to protect your capital from self-inflicted slippage.
1. The Anatomy of an "Air Pocket": Healthy Books vs. Hollow Books
The primary reason a modest $10,000 order moves an altcoin by 5% is the presence of Air Pockets in the Level-2 order book.
Let’s contrast the Level-2 Ask ladder of a high-liquidity asset (Bitcoin) with an illiquid mid-cap altcoin (Token XYZ):
[ HEALTHY HIGH-LIQUIDITY BOOK (BTC/USDT) vs. HOLLOW LOW-LIQUIDITY BOOK (XYZ/USDT) ]

  BITCOIN LEVEL-2 ASKS (Thick & Dense):        ALTCOIN XYZ LEVEL-2 ASKS (Hollow Air Pockets):
  ┌──────────────┬────────────┬─────────────┐  ┌──────────────┬────────────┬─────────────┐
  │  PRICE ($)   │ SIZE (BTC) │ CUMULATIVE  │  │  PRICE ($)   │ SIZE (XYZ) │ CUMULATIVE  │
  ├──────────────┼────────────┼─────────────┤  ├──────────────┼────────────┼─────────────┤
  │  $65,001.00  │  1.50 BTC  │ $97,501.50  │  │    $1.050    │  3,200 XYZ │ $10,815.00  │ ◄── HUGE +5.0% GAP!
  │  $65,000.80  │  2.20 BTC  │ $240,503.26 │  │    $1.035    │  1,100 XYZ │ $7,455.00   │
  │  $65,000.50  │  0.80 BTC  │ $292,503.66 │  │    $1.020    │    800 XYZ │ $6,318.00   │ ◄── EMPTY GAP
  │  $65,000.20  │  3.10 BTC  │ $494,004.28 │  │    $1.005    │  2,500 XYZ │ $5,502.00   │
  │  $65,000.00  │  5.00 BTC  │ $819,004.28 │  │    $1.000    │  3,000 XYZ │ $3,000.00   │ ◄── TOP OF BOOK
  └──────────────┴────────────┴─────────────┘  └──────────────┴────────────┴─────────────┘
  A $10,000 Market Buy moves price $0.15 (0.0002%)!  A $10,000 Market Buy sweeps up to $1.050 (+5.0%)!
Why the Altcoin Book Creates a Violent Price Spike:
The single $10,000 order violently swept through five distinct price tiers, leaving the last traded print at $1.050 (+5.0%).
2. The DEX AMM Reality: The Invariant Curve ($x \cdot y = k$)
On decentralized exchanges (Uniswap, PancakeSwap, Raydium), the dynamic is governed not by limit order queues, but by constant product liquidity pools:
x · y = kWhere $x$ is the reserve of the base token (e.g. XYZ) and $y$ is the quote asset reserve (e.g. USDC).
[ THE CONSTANT PRODUCT PRICE IMPACT CURVE ]

  POOL RESERVES: 100,000 XYZ ($100k) + 100,000 USDC ($100k) ──► Total Pool TVL: $200,000
  Starting Spot Price: $1.00 USDC per XYZ

  INCOMING SWAP: Buy with $10,000 USDC (Only 5% of total pool TVL!)
  ────────────────────────────────────────────────────────────────────────
  New USDC Reserve (y'):  100,000 + 10,000 = 110,000 USDC
  Invariant Constant (k):  100,000 · 100,000 = 10,000,000,000
  New XYZ Reserve (x'):   10,000,000,000 / 110,000 = 90,909.09 XYZ
  XYZ Received by Trader:  100,000 - 90,909.09 = 9,090.91 XYZ

  Average Realized Price:  $10,000 / 9,090.91 = $1.100 USDC per XYZ (+10.0% Effective Cost!)
  New Marginal Spot Price: (110,000 / 90,909.09) = $1.210 USDC (+21.0% Pool Shift!)
Notice what happened: A $10,000 swap in a $200k liquidity pool caused an immediate 10% realized slippage penalty and shifted the marginal pool price by +21%.
Because the pricing formula is non-linear, as trade size approaches even a small fraction of the pool’s reserves, price impact accelerates exponentially.
3. The "Thin Tape" Domino Effect: Why Spikes Get Magnified
When an order book is hollow, a market order does not just cause immediate mechanical slippage—it triggers a chain reaction across algorithmic participants:
[ THE THREE-STAGE LIQUIDITY CASCADE ]

  1. RETAIL $10,000 MARKET BUY CLEARS AIR POCKETS
     │ (Price spikes +5% in 800ms)
     ▼
  2. MARKET MAKER ALGORITHMS RETRACT QUOTES
     │ (HFT bots cancel passive asks at +6% to avoid toxic flow)
     ▼
  3. STOP-LOSS ORDERS & SHORT LIQUIDATIONS TRIGGER
     │ (Forced buying from stopped-out short positions pours into empty book)
     ▼
  4. PRICE EXPLODES HIGHER BEFORE COLLAPSING BACK TO BASELINE
     │ (Arbitrageurs from other venues dump inventory to harvest the gap)
Stage 1: Market Maker Quote Retraction
Automated market makers (AMMs and algorithmic CEX market makers) run risk management algorithms designed to protect their inventory from "toxic flow" (informed traders who know breaking news).
The millisecond an algorithm detects rapid sequential fills sweeping through three price levels, it assumes someone knows something critical. It instantly cancels its higher asks to avoid selling at a discount, creating even larger air pockets above the market.
Stage 2: Stop-Loss Triggers & Forced Liquidations
Traders holding short positions or trailing stop orders often place them just above key resistance levels. When the $10k spike punches through that level, those stop-losses become unconditional market buy orders, adding fuel to the fire.
Stage 3: The Arbitrage Mean-Reversion Dump
Once the spike peaks, cross-exchange arbitrage bots detect that Token XYZ is trading at $1.05 on Exchange A, while still trading at $1.00 on Exchange B.
The bots buy on Exchange B, transfer, and aggressively dump on Exchange A, smashing the price back down to $1.00.
The original buyer is left holding tokens bought at an average price of $1.035, while the market immediately reverts to $1.00—handing the buyer an instant -3.5% unrealized loss.
4. Market Cap vs. Real Liquidity: The 24h Volume Mirage
One of the most dangerous traps for altcoin traders is relying on Market Capitalization or 24-Hour Trading Volume on aggregators like CoinMarketCap or CoinGecko.
| Metric | What It Shows | What It Hides |
|---|---|---|
| Market Capitalization | Last Price $×$ Circulating Supply | Assumes all coins can be sold at the last traded price (completely false). |
| 24-Hour Reported Volume | Total gross trading turnover | Often 90%+ circular bot wash trading that provides zero real bid/ask depth. |
| $±2\%$ Order Book Depth | Real dollar capital waiting on the order book | The true measure of liquidity—reveals exactly how much cash is needed to move price by 2%. |
A coin can boast a $50,000,000 fully diluted valuation, but if only $6,000 of real cash sits in the $±2%$ order book, that market cap is an optical illusion.
5. Tactical Execution Guide: How to Trade Low-Liquidity Altcoins Safely
If you are accumulating or exiting positions in low-liquidity tokens, follow these four quantitative execution rules: