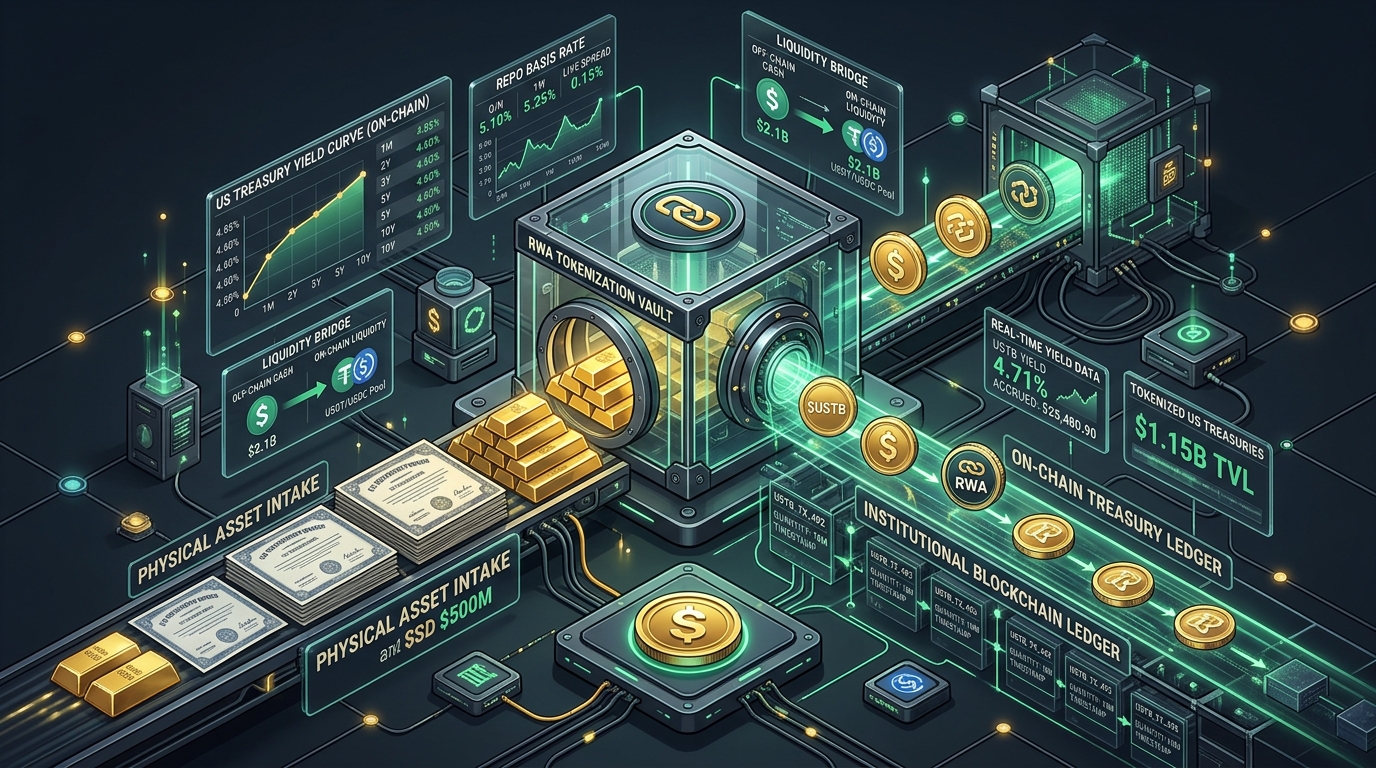
For the first decade of cryptocurrency, decentralized finance operated in a macroeconomic vacuum.
When global central banks maintained interest rates near 0%, DeFi yields of 8% to 15%—generated through recursive liquidity mining and speculative token emission programs—easily outshone traditional banking products. But when the Federal Reserve and global central banks launched the most aggressive monetary tightening cycle in forty years, driving risk-free sovereign yields above 5%, crypto’s speculative yields rapidly lost their luster.
The institutional response was immediate and transformative: bringing the multi-trillion-dollar market for sovereign real-world assets (RWAs) directly onto the blockchain.
Today, institutional fund managers like BlackRock (with the BUIDL token), Franklin Templeton (with FOBXX/BENJI), and Ondo Finance (with USDY and OUSG) manage billions of dollars in on-chain tokenized US Treasuries and repo agreements. Yet, because these assets exist at the friction-heavy intersection of strict KYC/AML legal frameworks and permissionless 24/7 decentralized secondary markets, they have created fertile ground for structural basis trading and yield arbitrage.
In this master guide, we explore the mechanical architecture of tokenized treasuries, evaluate secondary market liquidity dislocations, and demonstrate how quantitative desks capture institutional alpha.
1. The Architecture of Tokenized Sovereign Debt
How does a physical 3-month US Treasury bill sitting inside an institutional custodian (like BNY Mellon or State Street) become a cryptographic token on Ethereum or Solana?
The process follows a multi-tiered legal and operational custody structure:
- The Special Purpose Vehicle (SPV) / Cayman Fund: A legal entity is established in a tax-efficient jurisdiction that holds direct title to short-dated US Treasury bills (T-bills) and overnight reverse repurchase agreements (repo) backed 100% by sovereign collateral.
- The Transfer Agent & Token Smart Contract: A registered transfer agent maintains the off-chain shareholder registry and synchronizes with an on-chain smart contract that mints and burns compliant tokens (such as ERC-20, ERC-3643, or ERC-1400 standards).
- Daily Oracle NAV Attestation: Every business day at market close (typically 4:00 PM EST), independent fund administrators and valuation oracles publish the fund’s official Net Asset Value (NAV) per token onto the blockchain.
2. Rebasing vs. Value-Accruing Yield Tokenomics
Tokenized yield-bearing assets distribute interest through one of two primary architectural models:
- Rebasing Tokens (e.g., BlackRock BUIDL, Ondo USDY): The price of the token remains permanently pegged to $1.00 USD, while the user’s token balance automatically increases every day as yield accrues. If you hold 100,000 tokens at a 5.0% annualized yield, your wallet balance will increase by approximately 13.7 tokens daily.
- Value-Accruing / Accumulating Tokens (e.g., Ondo OUSG, Matrixdock STBT): The number of tokens in the investor’s wallet remains constant, while the redemption price per token increases over time. If you purchase 1,000 tokens at $100.00 each, after one year of 5.0% yield, each token can be redeemed for $105.00 from the primary issuer.
3. The On-Chain vs. Off-Chain Repo Basis: Why Yields Diverge
In traditional finance, the Federal Reserve’s overnight reverse repo facility and treasury repo markets tightly pin institutional short-term lending rates within a narrow band of 5 to 10 basis points.
In decentralized finance, however, stablecoin interest rates are dictated entirely by leveraged trading demand on protocols like Aave, Compound, and Morpho. This creates massive macroeconomic yield disparities:
[ THE MACROECONOMIC BASIS ARBITRAGE EQUATION ]

  OFF-CHAIN RISK-FREE BENCHMARK:          ON-CHAIN DEFI STABLECOIN YIELD:
  • 3-Month US T-Bills: 5.20%            • Aave v3 USDC Supply Rate: 3.10% (Bear/Calm Market)
  • Overnight Reverse Repo: 5.30%         • Aave v3 USDC Supply Rate: 14.50% (Bull Market)

  ARBITRAGE OPPORTUNITY 1 (Calm Market):  ARBITRAGE OPPORTUNITY 2 (Bull Market):
  Borrow on-chain USDC at 3.10%, mint     Redeem off-chain Treasuries at 5.20%,
  Tokenized Treasuries yielding 5.20%.    deploy capital to DeFi lending at 14.50%.
  Net Spread: +2.10% (210 bps) Risk-Free. Net Spread: +9.30% (930 bps) Cash Carry.
During periods of market consolidation, quantitative treasuries borrow low-cost stablecoins on DeFi lending markets and allocate directly into tokenized treasuries, locking in positive carry. Conversely, during aggressive bull runs, institutional capital exits tokenized treasuries to provide high-yield stablecoin liquidity to leveraged traders.
4. Secondary AMM Peg Deviations & The Whitelist Moat
Because primary minting and redemptions with institutional issuers (like BlackRock and Ondo) are subject to strict regulatory whitelisting (KYC/AML approval, minimum $100k+ ticket sizes, and 24-to-48-hour banking settlement windows), retail and non-whitelisted traders can only trade tokenized RWAs on decentralized AMMs (such as Curve pools or Uniswap v3).
This creates significant secondary market price dislocations:
- When a large crypto fund needs immediate liquidity on a weekend or during an on-chain liquidation event, they cannot wait for traditional US banking hours (Fedwire) to redeem their tokenized treasuries.
- Instead, they execute a market sell order directly against decentralized Curve liquidity pools, dumping the tokenized RWA for USDC or USDT.
- This sudden selling pressure drives the secondary AMM price down to $0.9920 to $0.9960 (a 40 to 80 basis point discount against its real NAV of $1.0000).
5. Executing the Primary-to-Secondary Whitelist Arbitrage Loop
For institutional desks with verified access to both the primary issuer and secondary DEX markets, these discounts represent one of the purest, lowest-risk arbitrage strategies in modern finance:
- Detection: Identify that a tokenized treasury asset (e.g. Ondo USDY) has slipped to $0.9940 on a secondary Curve pool while its official NAV is $1.0000.
- Secondary Market Purchase: Purchase $2,000,000 worth of USDY from the Curve pool using liquid on-chain USDC at the discounted $0.9940 price (spending $1,988,000).
- Primary Redemption: Submit a formal redemption request for the $2,000,000 USDY directly to the issuer’s transfer agent.
- Fiat Settlement & Rebalancing: The issuer burns the tokens and wires $2,000,000 USD back to the fund’s institutional bank account via Fedwire, generating a clean +$12,000 profit (60 bps) in under 48 hours.
- On-Ramp & Repeat: Convert the USD back to USDC via zero-fee institutional minting (e.g., Circle Mint) and repeat the cycle.
6. Risk Factors & Structural Frictions to Consider
While RWA arbitrage offers attractive risk-adjusted returns, quantitative operators must carefully evaluate five critical structural frictions:
| Friction Vector | Impact on Strategy | Mitigation Protocol |
|---|---|---|
| Banking Settlement Latency | Fedwire operates exclusively 9:00 AM – 5:00 PM EST on banking business days; weekend redemptions incur 48-to-72-hour carry cost | Pre-fund liquid operating float on both on-chain and off-chain venues |
| Smart Contract & Upgradeability Risk | Institutional tokens utilize upgradeable proxy contracts with blacklisting functions | Audit proxy admin multi-sig keys and timelock delays |
| Issuer Insolvency & Bankruptcy Remoteness | Counterparty risk if underlying SPV assets are not properly segregated | Verify independent bankruptcy-remote legal opinions and proof-of-reserve oracles |
| Gas & Secondary DEX Slippage | On-chain swap slippage on illiquid AMM pools can erode small basis spreads | Calculate break-even slippage thresholds using quantitative calculators |
7. Quantitative Execution & Tooling Integration
- Track Real-Time Liquidity Disparities: Use our Live Arbitrage Scanner to monitor live price gaps between pegged stable assets and secondary exchange order books.
- Calculate Net Margin After Banking & Gas Fees: Always input wire fees, token burn fees, and network gas costs into our Profit & Break-Even Calculator before entering a multi-day redemption trade.
- Compare Exchange Liquidity Profiles: Evaluate centralized exchange fiat gateway depth using our Global Exchanges Directory to optimize your on/off-ramp execution speed.