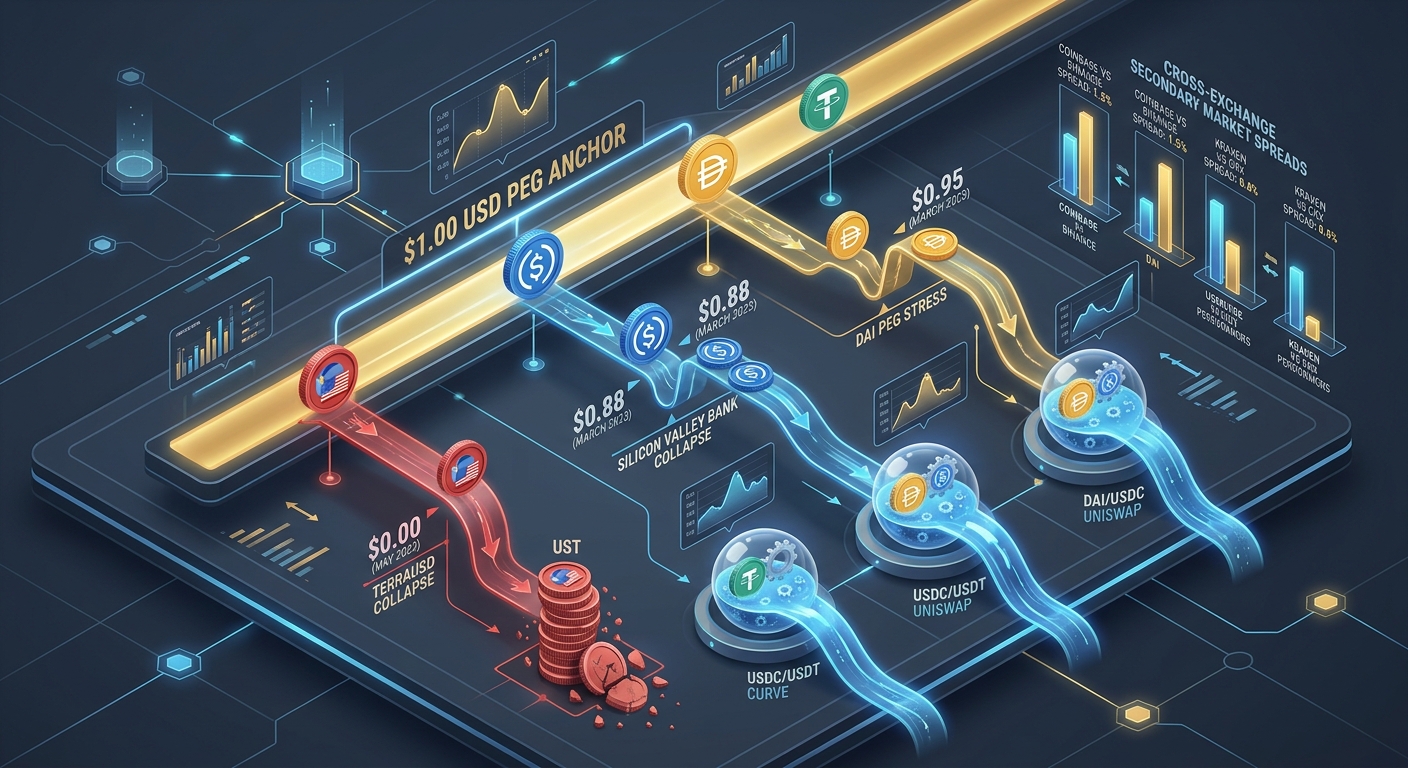
The foundational promise of a fiat-backed cryptocurrency is deceptively simple: One digital token is always worth exactly one United States Dollar ($1.0000).
Most crypto traders treat this as an immutable law of physics. They keep their life savings in USDT or USDC, use them as collateral for leverage, and treat them as equivalent to cash in a bank vault.
The reality of market microstructure is far more volatile.
Over the past decade, virtually every major stablecoin in existence—including Tether (USDT), USD Coin (USDC), MakerDAO (DAI), and Terra (UST)—has violently broken below the critical $0.9900 threshold.
During extreme banking crises and collateral runs, stablecoins have traded at $0.95, $0.88, $0.72, and in catastrophic structural collapses, all the way down to $0.00.
When these dislocations happen, they create some of the largest, most profitable, and most dangerous cross-exchange spread arbitrage opportunities in quantitative finance.
In this forensic quantitative retrospective, we map every major stablecoin depeg event in crypto history, examine the order book mechanics of the Curve 3pool, reconstruct the cross-exchange spreads, and evaluate what separated quick fortunes from total liquidation.
The Master Historical Stablecoin Depeg Matrix
The table below summarizes the most significant stablecoin depeg incidents in crypto history, the lowest secondary market price printed, the spread duration, and the ultimate recovery outcome:
| Stablecoin & Ticker | Date of Crisis | Lowest Price Printed (DEX / CEX) | Peak Discount Spread | Primary Root Cause | Eventual Resolution |
|---|---|---|---|---|---|
| 1. USD Coin (USDC) | March 10–13, 2023 | $0.8770 (Curve) / $0.8850 (Coinbase) | -12.30% Discount | Silicon Valley Bank ($3.3B trapped reserves) | 100% Peg Restored (FDIC fully backstopped SVB) |
| 2. MakerDAO (DAI) | March 10–13, 2023 | $0.8920 (Uniswap v3) | -10.80% Discount | PSM Collateral Exposure (52% USDC backing) | 100% Peg Restored (Followed USDC back to $1.00) |
| 3. Tether (USDT) | October 15, 2018 | $0.9200 (Kraken) / $0.8500 (Bitfinex) | -8.00% to -15.00% | Noble Bank insolvency & audit FUD | 100% Peg Restored (Tether honored 1:1 redemptions) |
| 4. Tether (USDT) | May 12, 2022 | $0.9480 (Coinbase Pro / FTX) | -5.20% Discount | Post-Terra Contagion & Liquidity Run | 100% Peg Restored (Tether processed $10B redemptions) |
| 5. TerraUSD (UST) | May 9–14, 2022 | $0.0080 (Total Collapse) | -99.20% Death Spiral | Algorithmic mint/burn reflexive death spiral | PERMANENT ZERO (Ecosystem collapsed to $0.00) |
| 6. TrueUSD (TUSD) | January 15–18, 2024 | $0.9620 (Binance spot) | -3.80% Discount | Attestation opacity & Binance Launchpool sell-offs | Partial Recovery (Gradual market cap drain) |
| 7. USDD (Decentralized USD) | November 2022 | $0.9690 (Huobi / Poloniex) | -3.10% Discount | FTX contagion & reserve pool asset imbalance | Stabilized at $0.98–$0.99 (Over-collateralized buffer) |
1. The Anatomy of a Depeg: Secondary Market Dislocation vs. Primary Redemption
To understand why a stablecoin trades below $0.99, you must grasp the fundamental split between the Primary Issuance Market and the Secondary Trading Market:
[ THE DUAL-MARKET STABLECOIN VALUATION ENGINE ]

  1. PRIMARY REDEMPTION MARKET (Institutional Whitelist Only):
     - Issuer (Circle / Tether Treasury):
     - 1 Token IN -> Exactly $1.0000 USD OUT (Minus 0.10% redemption fee).
     - Latency: 24 to 72 business hours (Requires active banking rails & KYC).

  2. SECONDARY TRADING MARKET (Public Order Books & AMMs):
     - Venues: Binance, Coinbase, Uniswap, Curve 3pool.
     - Pricing Engine: Real-time supply & demand governed by panic, liquidity, and immediate fear.
     - Latency: Sub-second / Microsecond real-time execution.
The Structural Friction: When panic strikes on a Friday night (such as when Silicon Valley Bank collapsed), the primary redemption window at Circle is closed for the weekend. The secondary market is completely on its own.
Without immediate 1:1 arbitrage redemption available to absorb the panic selling, secondary market prices can decouple violently until banking rails reopen on Monday morning.
Case Study 1: The Great USDC Depeg (March 2023) — The $0.877 Disaster
On Friday evening, March 10, 2023, California regulators shut down Silicon Valley Bank. At 10:11 PM EST, Circle confirmed it had $3.3 billion of its $40 billion USDC cash reserves stranded inside the shuttered bank.
What the Cross-Venue Spread Looked Like:
[ MARCH 11, 2023: THE USDC SECONDARY MARKET COLLAPSE ]

  Venue / Pool                     USDC Price Printed     Spread vs. USDT / USD ($1.00)
  ----------------------------------------------------------------------------------------
  Curve 3pool (DEX AMM)            $0.8770                -12.30% (Pool reached 94% USDC!)
  Uniswap v3 (USDC/USDT)           $0.8810                -11.90%
  Coinbase Spot (USDC/USD)         $0.8850                -11.50% (Trading halted later)
  Kraken (USDC/USD)                $0.8890                -11.10%
  Binance (USDC/USDT)              $0.8800                -12.00%
The Curve 3pool "Hot Potato" Dynamic:
The Resolution & The $1.2B Arbitrage Bonanza:
Case Study 2: The Tether (USDT) Panic Runs (2018 & 2022)
Tether is the most liquid asset in cryptocurrency history, but it has survived two harrowing sub-$0.95 depeg crises.
Incident A: The October 2018 Noble Bank Crisis ($0.9200)
Incident B: The Post-Terra Contagion (May 12, 2022 — $0.9480)
Case Study 3: The Terra (UST) Algorithmic Death Spiral ($0.0080 Collapse)
The crucial lesson of stablecoin history is distinguishing between a Collateralized Reserve Depeg and an Endogenous Algorithmic Death Spiral:
Real-World Case Study 4: Cross-Exchange Stablecoin Triangular Basis ($180,000 Arbitrage)
During the March 2023 USDC crisis, an institutional quant fund executed an automated triangular basis loop across Binance, Kraken, and Coinbase: