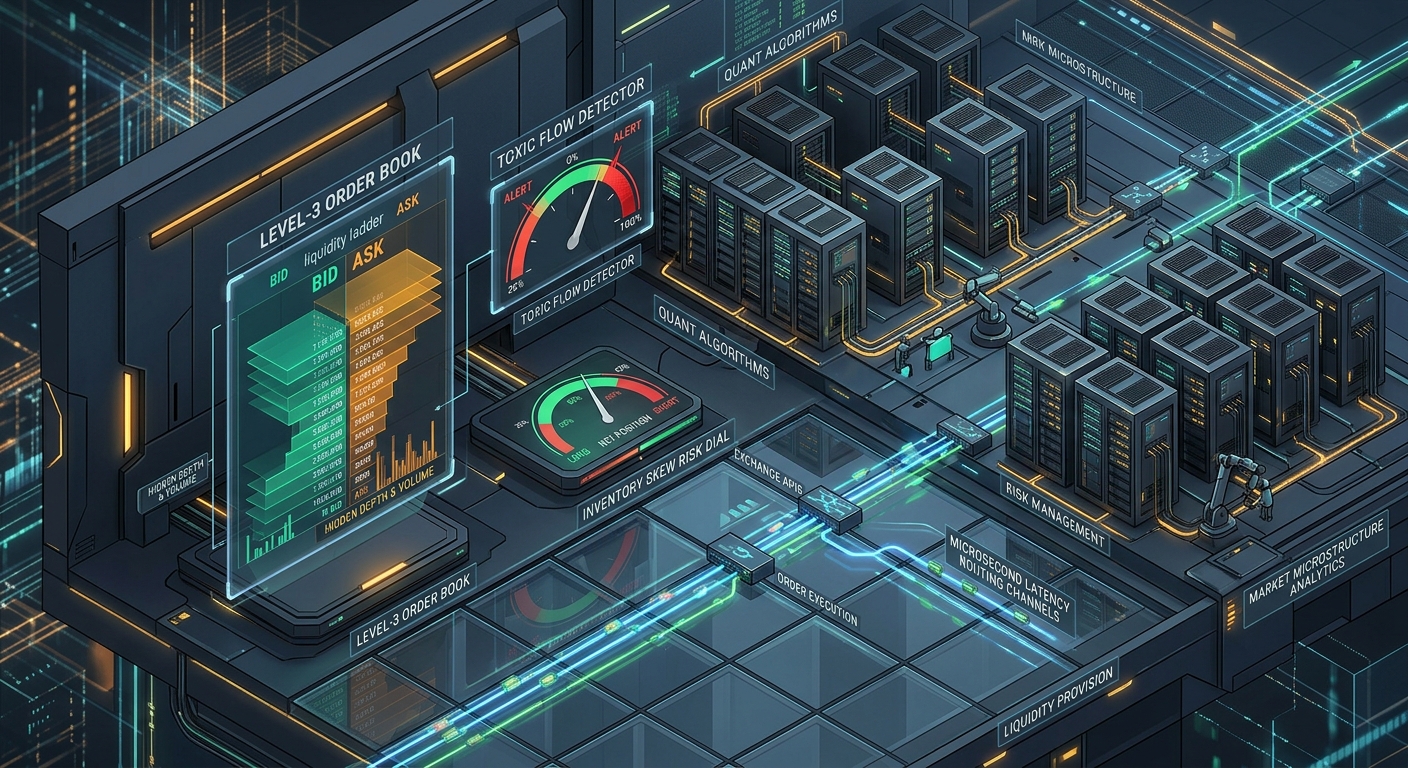
To the average cryptocurrency trader, the bid-ask spread is an annoying, minor nuisance—a tiny gap between the red numbers and the green numbers on an exchange terminal.
Retail traders look at Bitcoin quoting $64,500.00 Bid / $64,500.50 Ask and think: "The spread is $0.50. It is practically zero. The market is completely efficient."
To a quantitative market maker (MM) running high-frequency algorithms at Jump Trading, Wintermute, or Citadel Securities, that $0.50 spread is the battlefield of market microstructure.
Market makers do not quote prices to be helpful. Every resting bid and ask in an order book is a calculated risk calculation balancing inventory holding cost, latency asymmetry, adverse selection from toxic order flow, and exchange rebate economics.
In this forensic deep-dive, we pull back the curtain on the institutional mechanics of cryptocurrency order books. We will break down what market makers know, the equations they use to price spreads, and how you can stop getting trapped by their liquidity illusions using our Live Arbitrage Scanner.
1. The 4 Invisible Components of Every Spread
In classical financial economics (the Roll, Ho-Stoll, and Glosten-Milgrom microstructure frameworks), a bid-ask spread ($S$) is decomposed into four distinct risk premiums:
S = C_{processing} + C_{inventory} + C_{volatility} + C_{adverse selection}| Component | What It Represents | Why Market Makers Widen the Spread |
|---|---|---|
| 1. Order Processing Cost ($C_{\text{proc}}$) | Exchange connectivity, colocation servers, API rate limits, and clearing overhead. | Minimum baseline fee required to maintain operational infrastructure. |
| 2. Inventory Holding Risk ($C_{\text{inv}}$) | The capital risk of holding large amounts of volatile crypto tokens on balance sheet overnight. | Widens when the market maker is long too much inventory during a downtrend or short during a pump. |
| 3. Volatility Drag ($C_{\text{vol}}$) | Expected price variance ($\sigma^2$) over the market maker's order replacement cycle ($Delta t$). | Widens exponentially during breaking news (CPI releases, SEC announcements, exchange hacks). |
| 4. Adverse Selection / Toxic Flow Tax ($C_{\text{adv}}$) | The probability ($\alpha$) that an incoming market order is executed by an "informed trader" with superior speed or private information. | The dominant component (accounting for 50% to 80% of altcoin spreads). If toxic flow spikes, market makers pull quotes or widen spreads by 5x to 20x. |
2. Adverse Selection & The "Toxic Flow" Tax (Glosten-Milgrom Decoded)
The single most important concept in market making is Adverse Selection.
Suppose a market maker quotes bids and asks for Solana (SOL). Incoming orders fall into two categories:
[ THE TOXIC FLOW DILEMMA ]

  1. Market Maker quotes SOL Bid at $145.00 (resting limit order)
  2. Whale dumps $50M BTC on Binance. SOL fair value instantly collapses to $142.50.
  3. Before MM's cancellation packet arrives (due to 12ms network latency),
     an HFT Arbitrage Bot executes the MM's $145.00 bid!
  4. MM is filled at $145.00 on an asset now worth $142.50.
  5. INSTANT LOSS: -$2.50 per SOL on the filled inventory.
To survive this continuous threat of being "picked off" by faster algorithms, market makers must charge a toxic flow tax on every single quote. The wider the spread, the larger the buffer against informed traders.
This explains why low-cap altcoins have 1.50% spreads even on exchanges with decent volume: market makers know that anyone trading large volume on an obscure token probably knows something they don't.
3. Inventory Skewing: Why Quoted Prices Aren't Fair Value
Retail traders assume that the mid-market price $\frac{\text{Bid} + \text{Ask}}{2}$ represents the market's unbiased estimate of fair value.
Market makers know this is frequently false.
Under the Avellaneda-Stoikov model, a market maker with excess inventory will intentionally skew their quotes to induce retail traders into taking the other side of the trade:
[ INVENTORY SKEWING IN ACTION: AVELLANEDA-STOIKOV MODEL ]

Scenario: Market Maker accumulated 500 ETH ($1,700,000) and wants to reduce risk.

True Fair Value: $3,400.00

Unskewed Symmetric Quotes:
  - Bid: $3,399.50  (MM wants to buy)
  - Ask: $3,400.50  (MM wants to sell)

SKEWED INVENTORY QUOTES (MM discourages buys, aggressively attracts buyers):
  - Bid: $3,396.00  (Deeply discounted bid -> nobody will sell to MM)
  - Ask: $3,400.10  (Extremely attractive ask -> retail rushes to buy from MM!)

Result:
  - Midpoint appears to be $3,398.05 (Retail thinks market is dropping)
  - Retail buys all 500 ETH from the MM at $3,400.10
  - MM successfully dumps inventory at full price without taking market slippage!
When retail technical analysts see a "support wall" or "tight ask quote", they often misinterpret it as bullish sentiment, when in reality it is simply an institutional desk offloading risk before a volatility event.
4. Phantom Liquidity & The Level-2 Mirage
When retail traders look at an order book depth chart displaying $2,000,000 in resting asks within 0.5% of the ticker price, they feel confident that a $50,000 market buy will suffer minimal slippage.
What they don't know is that up to 75% of that depth is "Phantom Liquidity":
5. The Maker Rebate Asymmetry: How MMs Profit When Retail Loses
Why do professional market makers happily quote spreads as narrow as 1 to 2 basis points (0.01% to 0.02%) when retail trading fees are 0.10%?
Because institutional market makers do not pay fees—exchanges pay them to trade:
| Tier / Participant | Role | Typical Exchange Fee / Rebate | Net Profit on a 0.03% Spread |
|---|---|---|---|
| Retail Trader | Taker (Market Order) | +0.100% Fee | -0.070% Net Loss (Wiped out by fees) |
| Active Pro Trader | Taker (VIP 1) | +0.050% Fee | -0.020% Net Loss |
| Institutional MM | Maker (Resting Limit) | -0.005% Maker REBATE (Paid by exchange) | +0.040% Net Profit (Captures spread + 2x rebates) |
On a $100,000,000 monthly turnover desk, a -0.005% maker rebate generates $5,000 in pure exchange cash subsidies every single month, completely separate from spread capture profits.
6. How Retail Quants Can Exploit This Knowledge
Now that you understand the hidden microstructure behind crypto spreads, you can adapt your execution strategy to avoid getting exploited: