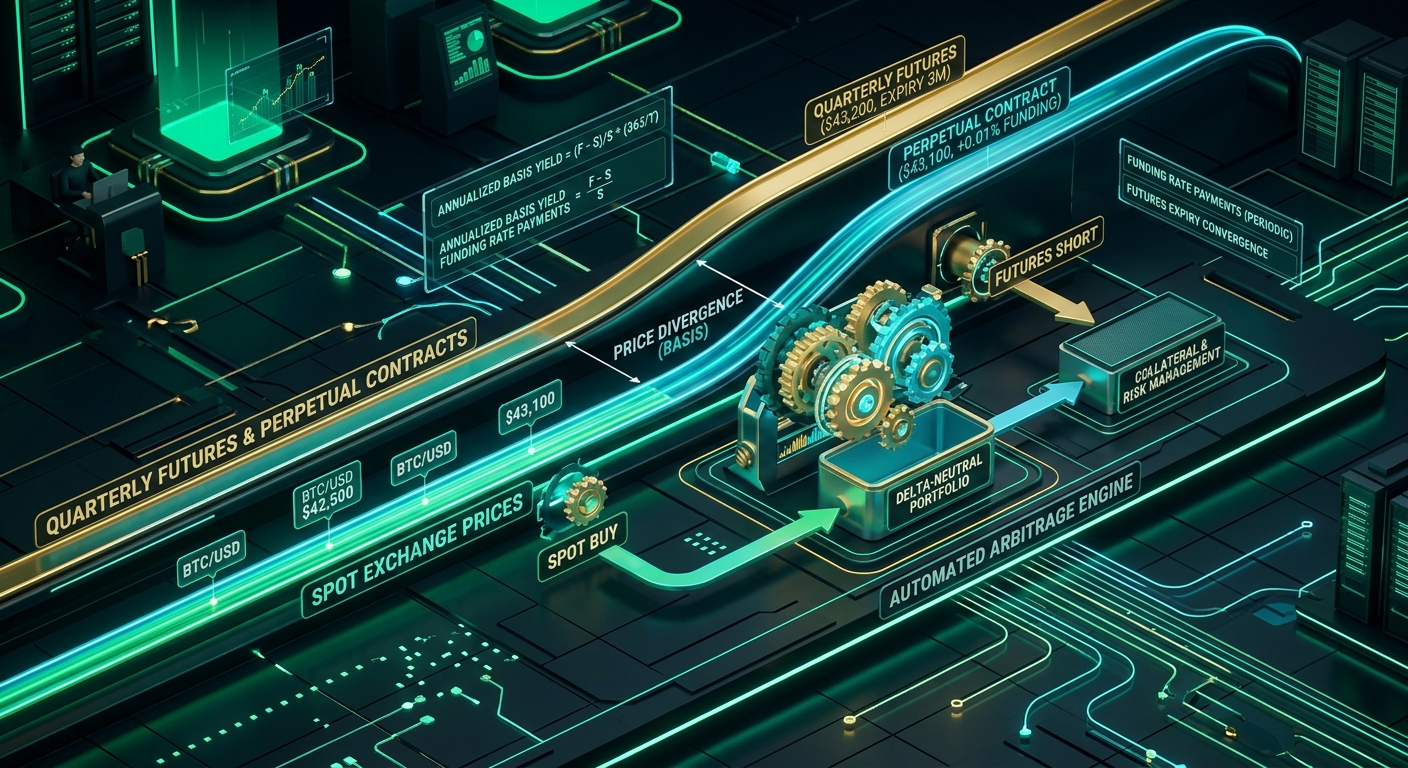
If you look at the cryptocurrency markets on any given day, you will quickly notice a peculiar paradox:
Spot Bitcoin on Coinbase is trading at $64,000.
Yet on the Chicago Mercantile Exchange (CME) and Binance, the 3-month quarterly Bitcoin futures contract is trading at $66,200.
Why would rational investors willingly pay a $2,200 premium for Bitcoin they won't even receive for another 90 days, when they could buy the exact same asset instantly for cheaper on the spot market?
This price differential is called The Basis.
Far from being a market defect, the basis is the beating heart of modern institutional trading. It serves as the primary gauge of market leverage sentiment and forms the foundation of the "Cash-and-Carry" Basis Trade—a multi-billion-dollar delta-neutral strategy that generates predictable, double-digit annualized yields without taking any directional market risk.
In this guide, we break down the physics of spot-futures price divergence, explore how perpetual funding rates keep crypto markets tethered, and walk through the exact mechanics hedge funds use to harvest basis profits.
1. What Is the Basis? (The Cost of Carry Formula)
In traditional finance, the theoretical price of a futures contract is determined by the Cost of Carry Model:
[ THE CLASSICAL COST OF CARRY EQUATION ]

  Futures Price = Spot Price × (1 + r - y)^T

  Where:
    • Spot Price = Current price to buy the asset today
    • r          = Risk-free interest rate (cost of financing)
    • y          = Convenience yield / Staking yield
    • T          = Time remaining until contract expiration (in years)
In traditional commodities (like crude oil or wheat), futures contracts trade at a premium to spot because the buyer avoids paying physical storage, insurance, and financing costs for three months.
In crypto, storing Bitcoin on a blockchain costs virtually nothing. Why, then, is the crypto basis premium often three to five times higher than traditional financial markets?
The answer is unquenchable demand for leverage.
2. Contango vs. Backwardation: The Two Market Regimes
The relationship between spot and futures prices takes two distinct structural shapes:
[ MARKET REGIME CURVES ]

  Price ($)
    ▲
    │                   / (Futures > Spot: CONTANGO / Bullish Leverage)
    │                  /
    │═════════════════/══════ Spot Price Baseline ($64,000)
    │                /
    │               /   (Futures < Spot: BACKWARDATION / Panic Shorting)
    └──────────────┴──────────────────────────► Time to Expiry (Months)
                 Spot    1-Month   3-Month   6-Month
1. Contango (The Bull Market Regime: Futures > Spot)
When market sentiment is bullish, retail and institutional traders want maximum upside exposure. Rather than posting 100% cash to buy spot Bitcoin, they post a 10% margin deposit to buy long futures contracts.
This overwhelming demand to buy leverage drives futures prices well above the spot price, putting the market into Contango.
2. Backwardation (The Bear Market Regime: Futures < Spot)
During panic sell-offs or liquidity crunches, aggressive short sellers dump futures contracts to hedge their portfolios, while leverage long positions get liquidated.
When futures trade at a discount to spot, the market enters Backwardation. Spot holders who urgently need cash sell spot at a premium, while futures buyers demand a steep discount to take on forward risk.
3. Step-by-Step: The "Cash-and-Carry" Basis Arbitrage
The basis trade is widely considered the holy grail of quantitative hedge funds (such as Millennium Management, Jane Street, and Point72).
Here is the step-by-step anatomy of how a Cash-and-Carry Basis Trade executes in real life:
[ THE CASH-AND-CARRY ARBITRAGE BLUEPRINT ]

  Market Conditions:
    • Spot Bitcoin Price (Coinbase):      $64,000
    • 3-Month CME Futures Expiry Price:    $66,240 (+3.5% premium, 90 days out)

  Execution (Zero Directional Risk):
    Step 1: Quant fund purchases 100 Spot BTC at $64,000 (Capital deployed: $6,400,000).
    Step 2: Simultaneously, fund SELLS (shorts) 100 BTC of 3-month futures at $66,240.

  What happens at Expiration (Day 90)?
    • By contract design, on expiration day, the Futures Price MUST converge with the Spot Price!

  Scenario A (Bitcoin moons to $100,000):
    • Spot Profit:   +$3,600,000 ($100k - $64k × 100)
    • Futures Loss:  -$3,376,000 ($66,240 - $100k × 100)
    • NET PROFIT:    +$224,000 (Exactly the initial $2,240 basis spread!)

  Scenario B (Bitcoin crashes to $30,000):
    • Spot Loss:     -$3,400,000 ($30k - $64k × 100)
    • Futures Gain:  +$3,624,000 ($66,240 - $30k × 100)
    • NET PROFIT:    +$224,000 (Still exactly the $2,240 basis spread!)
Annualized Return Calculation:
Annualized Yield = (Basis Spread / Spot Price) × (365 / Days to Expiry)Annualized Yield = ($2,240 / $64,000) × (365 / 90) = 3.50% × 4.055 = 14.19% APR!Regardless of whether Bitcoin goes to $1,000,000 or $0, the fund locks in a 14.19% risk-free annualized dollar return.
4. Perpetual Swaps & The Funding Rate Mechanism
Traditional calendar futures expire every quarter (March, June, September, December). But in crypto, over 80% of volume trades on Perpetual Futures (Perps), which have no expiration date.
Without an expiration date to force convergence, what stops a perpetual contract from drifting $5,000 away from the spot price?
The Funding Rate Engine.
Every 8 hours, exchanges (Binance, Bybit, OKX, Hyperliquid) calculate a funding payment exchanged directly between long and short traders:
[ THE PERPETUAL FUNDING RATE FEEDBACK LOOP ]

  If Perp Price > Spot Price (Bullish Bias):
    • Funding Rate is POSITIVE (+0.03% every 8h).
    • Longs must PAY shorts every 8 hours.
    • Economic Pressure: Longs close positions to avoid fees -> Perp price falls back to Spot.

  If Perp Price < Spot Price (Bearish Bias):
    • Funding Rate is NEGATIVE (-0.02% every 8h).
    • Shorts must PAY longs every 8 hours.
    • Economic Pressure: Shorts close positions to avoid fees -> Perp price rises back to Spot.
This periodic cash transfer ensures perpetual futures prices stay tightly anchored to the underlying spot index within fractions of a percent.
5. Why Basis Spreads Widen: The 4 Structural Forces
Even with thousands of arbitrage bots operating around the clock, why do basis spreads continue to widen during volatile market cycles?
| Market Force | Microstructure Impact | Real-World Manifestation |
|---|---|---|
| 1. Retail Leverage Surges | Massive influx of retail market orders bidding up perpetuals and futures contracts. | Spreads expand to 20%+ annualized basis during major bull market breakouts. |
| 2. Exchange Counterparty Risk | Capital deposited on offshore derivative exchanges is exposed to exchange insolvency risk. | Traders demand a higher basis premium to compensate for platform counterparty risk. |
| 3. Collateral & Capital Inefficiency | Arbitrageurs must split capital between spot and derivatives margin accounts. | During sudden volatility, margin call liquidation risks limit the size arbitrageurs can deploy. |
| 4. Banking & Fiat Transfer Latency | Traditional bank wires take 24–48 hours to rebalance fiat capital between spot brokers and futures desks. | Weekend and holiday liquidity droughts cause multi-day basis divergence. |
6. Quantitative Takeaways & Execution Checklist
Whether you are looking to deploy capital into delta-neutral basis trades or simply want to optimize your trading execution, keep these rules in mind: